
Blogs
Tissue Paper Converting Machines Market: Why 4.5% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Tissue Paper Converting Machines Market
The tissue paper converting machines market stands at a pivotal juncture, shaped by steady demand growth, technological evolution, and a shifting regulatory landscape. Over the past five years, the market has expanded from approximately 1,200 million USD in 2020 to roughly 1,550 million USD in 2025, reflecting a compound annual growth rate of around 4.5 percent through 2032. This trajectory signals more than a simple volume increase; it indicates a structural reconfiguration of how tissue products are manufactured, packaged, and distributed. For executives and investors, the question is no longer whether demand will persist, but how operational strategies must adapt to capture margin, resilience, and relevance in a market that is simultaneously consolidating and fragmenting.
Mapping the Market Canvas
The market's current scale reflects a mature but still expanding base. The growth from 2020 to 2025 has been underpinned by consistent household and commercial consumption, retrofit activity on aging converting lines, and incremental automation upgrades. Looking ahead to 2032, the projected expansion to more than 2.1 billion USD suggests that conversion capacity will continue to grow, though the pace and geographic distribution will vary. The revenue concentration among the top three players, at roughly 42 percent, and the top five at around 58 percent, indicates a moderately consolidated field where scale, technology access, and service networks provide meaningful advantages. Yet the remaining share is distributed across a diverse set of manufacturers, regional specialists, and cost-oriented entrants, creating a competitive environment where differentiation increasingly hinges on reliability, integration capability, and speed to market rather than price alone.
Key Challenges and Inflection Points
The sector faces a cluster of interrelated challenges that are reshaping investment and deployment decisions.
Tissue Paper Market
- Regulatory pressure on pulp traceability and sourcing. The EU Deforestation Regulation, which took full effect in late 2024, requires traceability of wood pulp used in tissue production. This regulation is not merely a compliance checkbox; it alters supplier qualification processes, documentation workflows, and procurement risk for converters who must now demonstrate chain-of-custody integrity for raw materials.
- Trade and tariff volatility affecting input costs. Geopolitical trade tensions, including U.S.-Canada-Mexico tariff dynamics, have introduced uncertainty into pulp and recovered-paper supply chains. Cost structures that were once predictable are now subject to shifts driven by policy changes, logistics disruptions, and currency movements.
- Demand for higher speeds, automation, and quality consistency. Rising consumption of hygiene products is driving investments in automation and high-speed converting lines, but this push collides with the need for flexibility. Operators must balance throughput with changeover efficiency, product differentiation, and shelf-ready packaging requirements, all while maintaining uptime and minimizing waste.
These challenges create a clear inflection point: manufacturers and converters can no longer treat converting equipment as a standalone capital purchase. Instead, decisions must account for upstream raw-material compliance, downstream packaging and logistics expectations, and the operational cost of downtime or rework.
PW Consulting Automotive & Machinery Research Center
Key Drivers Shaping the Market
Technological Innovation and Confluence of Automation
Innovation in tissue converting is moving beyond incremental speed gains toward integrated, intelligent line architectures. Leading equipment suppliers are emphasizing complete line integration that spans rewinding, folding, embossing, and packaging, reducing the need for standalone machines and simplifying changeovers. Trade show activity in 2025 and 2026 illustrates this direction: Futura S.p.A. showcased integrated converting lines at Tissue World Miami in 2026, while Gambini S.p.A. completed its North American market offer with new Comparable-TADs and TAD converting line previews at Miami events the same month. OMET presented tissue converting solutions at MIAC 2026 in Lucca, and PCMC highlighted innovations including the Meridian Elite+ at FTA FORUM INFOFLEX 2026. United Converting Tissue S.r.l. emphasized simplified, reliable converting solutions at Tissue World Düsseldorf 2025. These appearances reflect a broader pattern: manufacturers are positioning integrated, automation-ready platforms that can be configured for multiple product formats, with an emphasis on maintenance simplicity and configuration flexibility.
For decision-makers, this trend means that equipment evaluation should extend beyond machine specifications to include total line productivity, compatibility with existing infrastructure, and the vendor's ability to support service, training, and spare-parts logistics. The value proposition is shifting from "how fast can it run" to "how reliably can it run across a range of products and changeovers."
Policy and Regulatory Environment as a Strategic Variable
Regulatory developments are increasingly embedded in capital planning. The EU Deforestation Regulation's traceability requirements for wood pulp are prompting converters to reassess supplier relationships and documentation processes. In parallel, geopolitical tariff dynamics affecting pulp and recovered paper supply chains are altering cost forecasting and sourcing strategies. These forces do not merely add compliance overhead; they influence which equipment configurations make sense. For example, lines that reduce material waste, support tighter quality control, and improve yield can soften the impact of input-cost volatility. Likewise, equipment that facilitates traceability and batch integrity can help converters meet regulatory expectations without compromising throughput.
The practical implication is that regulatory and trade considerations should be integrated into vendor selection, line design, and operational planning. Equipment that supports consistent quality, minimal waste, and clear process control can become a buffer against upstream uncertainty.
Demand-Side Shifts in Household and Commercial Settings
Demand for hygiene products continues to drive investments in automation and high-speed converting lines. The at-home retail segment remains the larger revenue pool, supported by staple household consumption, while the away-from-home commercial segment provides a complementary growth channel tied to hospitality, healthcare, and institutional use. These segments have different requirements: retail channels often emphasize shelf-ready packaging, consistent formatting, and brand presentation, while commercial channels may prioritize volume, reliability, and format flexibility. The result is a demand environment that rewards converters capable of serving multiple channels with adaptable equipment and efficient changeover protocols.
This demand diversity also encourages product differentiation. Folded tissue, paper napkins, toilet rolls, and kitchen rolls each carry distinct converting needs, and lines that can be configured across these formats offer downstream flexibility. In practical terms, converters are increasingly looking for equipment that can support product mix changes without sacrificing speed or quality, enabling them to respond to retail buyer requirements and commercial volume demands with greater agility.
Supply Chain and Cost Structure Realignment
The cost and sourcing environment is being reshaped by both environmental considerations and macroeconomic forces. Recovered paper has become a significant input in tissue production due to environmental concerns and cost-efficiency goals, and this shift influences not only raw-material procurement but also equipment requirements around fiber handling, consistency, and yield optimization. At the same time, tariff and trade tensions can affect pulp availability and pricing, prompting converters to think more carefully about inventory strategies, supplier diversification, and machine uptime.
From an equipment perspective, these supply-chain dynamics favor lines that support efficient material use, robust process control, and rapid troubleshooting. The cost of downtime is amplified when input costs are volatile or when compliance documentation must be maintained, making reliability and service responsiveness strategic priorities rather than operational niceties.
Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation Among Core Players
The competitive field combines established Western manufacturers with regional specialists and cost-oriented entrants. Several patterns are evident in how leaders are positioning themselves.
- Integrated line capability and automation focus. Companies such as Futura S.p.A. and Gambini S.p.A. emphasize integrated converting lines with automation enhancements, testing facilities, and product-format flexibility. Their positioning suggests a strategy built around end-to-end solutions, service ecosystems, and the ability to support both consumer and away-from-home products.
- Reliability and ease of configuration. United Converting Tissue S.r.l. promotes simplified, reliable lines for roll and folded products with a focus on ease of maintenance and configuration. This approach appeals to operators who value predictable performance, straightforward servicing, and lower complexity in daily operation.
- Specialization and format depth. OMET supplies automatic tissue converting lines, including ASV and AS models for interfolded and paper towel products, while 9. Septembar brings more than 40 years of specialization in napkins, facial tissue, and related products. C.G. Bretting Manufacturing Co., Inc. specializes in tissue and towel converting equipment including folders, interfolders, and custom lines. These players illustrate how format-specific expertise and custom configuration can create defensible niches.
- Cost-effective solutions and packaging integration. Baosuo Paper Machinery Manufacture Co., Ltd. manufactures tissue converting machines and full packaging systems with a focus on cost-effective solutions, reflecting a value-oriented positioning that can be attractive in price-sensitive deployment contexts.
- Complete lines under a broader industrial platform. Paper Converting Machine Company (PCMC), operating under Barry-Wehmiller, provides complete tissue converting lines including rewinding, folding, embossing, and packaging. Its structure highlights the advantage of being able to offer integrated equipment with broader industrial capabilities and service reach.
The strategic message is clear: differentiation is increasingly built on integration, automation, service reliability, and format flexibility. Price matters, but it is not the only axis of competition. Vendors that can reduce changeover friction, support consistent output, and deliver dependable after-sales support are positioning themselves to capture share in a market where downtime and quality variability carry real financial consequences.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market's concentration, with the top three firms holding roughly 42 percent and the top five around 58 percent, suggests room for both consolidation and specialized fragmentation. Consolidation can emerge through partnerships, acquisitions, or the expansion of integrated service networks, particularly among manufacturers that can offer complete lines and cross-region support. At the same time, fragmentation persists because regional demand patterns, product-format requirements, and cost structures differ enough to sustain local and niche players.
New entrants and regional specialists continue to find opportunities, especially where they can combine cost advantages with targeted format expertise or local service responsiveness. The presence of companies from North America, Italy, Serbia, and China reflects a geographically diverse supply base, each with distinct strengths. North American and Italian manufacturers often emphasize integration, automation, and brand recognition, while other regional players may compete on price, customization, or proximity to specific customer segments. This diversity means that buyers have more options but also face a more complex evaluation environment, where the right choice depends on product mix, throughput needs, compliance posture, and total cost of ownership.
Future Trends and Commercial Opportunities
Trend 1: Integrated, Automation-Ready Converting Lines as the Default Expectation
Over the next three to five years, integrated converting lines with automation-ready architectures are likely to become more common as operators seek to reduce complexity, improve uptime, and support multiple product formats. The commercial opportunity here lies in vendors and converters who can demonstrate measurable gains in changeover efficiency, waste reduction, and service responsiveness. For equipment makers, this trend favors platforms that are modular, configurable, and supported by strong documentation and service networks. For converters, it favors strategies that prioritize total line productivity over isolated machine specifications.
The risk is that automation and integration promises can outpace real-world implementation. Lines that appear seamless on paper may require significant site preparation, training, and process reengineering. Decision-makers should assess not only the equipment but also the operational changes required to realize the expected benefits.
Trend 2: Compliance and Traceability as Competitive Differentiators
Regulatory requirements such as the EU Deforestation Regulation, combined with ongoing trade and tariff volatility, are elevating traceability and sourcing integrity from operational concerns to strategic differentiators. Over the coming years, converters that can demonstrate reliable chain-of-custody practices and consistent quality control may gain advantages in buyer qualification, market access, and risk management. Equipment and process designs that support batch integrity, documentation, and material efficiency will become more valuable.
The opportunity is twofold: converters can use compliance readiness as a selling point to retailers and commercial buyers, and equipment suppliers can highlight features that support traceability and material control. The risk is that compliance requirements may intensify, requiring ongoing updates to documentation, supplier qualification, and internal controls. Organizations that treat compliance as a one-time project rather than a continuous capability may face recurring friction.
Trend 3: Demand Diversity Driving Format Flexibility and Channel-Specific Solutions
The coexistence of strong at-home retail demand and steady away-from-home commercial demand is likely to sustain a need for format flexibility and channel-aware converting strategies. Folded tissue, paper napkins, toilet rolls, and kitchen rolls each require different handling, and retail channels often place additional emphasis on shelf-ready packaging and presentation. As a result, converters that can shift between formats efficiently and adapt packaging to channel expectations will be better positioned to capture demand across segments.
The commercial opportunity lies in equipment and service models that support rapid reconfiguration, consistent output across formats, and packaging integration that aligns with retail or commercial requirements. The risk is that trying to serve too many formats without sufficient process control can erode quality and uptime. The most successful operators will likely be those that define a clear product-mix strategy and match equipment and staffing to that strategy, rather than pursuing maximum flexibility without operational discipline.
Box Making Machines Market
Actionable Guidance for Decision-Makers
For Manufacturers and Equipment Suppliers
- Position integration and support, not just speed. Buyers increasingly evaluate total line performance, changeover efficiency, and after-sales support. Emphasize configurations that reduce complexity, improve uptime, and accommodate multiple formats, and ensure service documentation, training, and spare-parts availability match the promised capability.
- Embed compliance and traceability into the value proposition. With traceability requirements and trade volatility affecting pulp and recovered-paper inputs, equipment that supports material efficiency, batch consistency, and process control can become a strategic asset. Highlight features that help converters manage input variability and documentation burdens.
- Sharpen segmentation by format and channel. Toilet rolls, kitchen rolls, folded tissue, paper napkins, and stand-alone systems each have distinct needs. Tailor offerings and messaging to these differences, and consider channel-specific packaging and configuration options that align with retail and commercial expectations.
For Investors and Strategic Buyers
- Evaluate total cost of ownership and service reach. In a market where downtime and quality variability carry real costs, service networks, training, and parts availability can be as important as initial capital cost. Assess vendors on their ability to deliver reliable support across the deployment lifecycle, not just on headline specifications.
- Watch for consolidation and capability bundling. The concentration among leading players suggests potential for further integration through partnerships or acquisitions that expand integrated-line offerings, service coverage, or regional reach. Check whether a vendor's roadmap includes stronger integration, automation, or compliance support that aligns with long-term market direction.
- Factor regulatory and trade risk into sourcing and planning. Pulp traceability, recovered-paper demand, and tariff dynamics can influence input costs and supplier stability. Diversify sourcing where possible, and favor equipment and processes that reduce waste and improve yield to buffer against volatility.
For Converters and Procurement Teams
- Align equipment choices with product-mix and channel strategy. Define the formats, throughput ranges, and packaging requirements that matter most to your market, then match equipment capability to that strategy. Avoid over-investing in flexibility that your operations cannot manage consistently.
- Prioritize reliability and changeover efficiency. In an environment of input-cost volatility and compliance demands, uptime and consistent output are critical. Evaluate changeover procedures, maintenance access, and training requirements alongside speed and automation features.
- Use compliance readiness as a commercial lever. If traceability and sourcing integrity matter to your buyers, ensure your processes and equipment support those expectations. This can become a competitive advantage in retail and commercial qualification, especially where buyers increasingly scrutinize supply-chain responsibility.
The tissue paper converting machines market is evolving from a volume-driven equipment space into a more nuanced environment where integration, compliance, format flexibility, and service reliability shape competitive outcomes. The data points to steady growth, but the real value lies in how organizations translate that growth into operational advantage. For those seeking a more detailed view of segment dynamics, regional patterns, and company-level positioning, a deeper dive into the full research report can provide the granular data and customized context needed to turn these trends into concrete plans.
For detailed analysis of this topic, please visit the official page: Tissue Paper Converting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electrophysiology Devices Market: How 10.95% CAGR Redefines Competition
By pmarketresearch, 2026-09-21
The Electrophysiology Device Market: Navigating a Decade of Transformative Growth
Market Current State and Core Challenges
The global electrophysiology (EP) device market has entered a phase of sustained expansion, driven by an aging population, the rising prevalence of cardiac arrhythmias, and rapid technological evolution. Historical data from 2020 through 2025 shows a consistent upward trajectory, with the market crossing the four billion dollar threshold in the base year. Projections extending through 2032 indicate that this growth momentum will not only persist but accelerate, supported by a compound annual growth rate that underscores the sector's resilience and strategic importance. This trajectory is not merely a function of volume; it reflects a fundamental shift in how electrophysiology procedures are conceptualized, executed, and reimbursed.
At the heart of this expansion lies a market structure that remains moderately concentrated. The top three players command nearly half of the total revenue, while the leading five collectively account for over two-thirds. This concentration suggests that scale, established clinical relationships, and comprehensive product portfolios continue to provide significant moats. However, the remaining market share, distributed among regional players and specialized innovators, indicates ample room for disruption and niche positioning. The balance between entrenched incumbents and agile newcomers defines the current competitive tension.
Worldwide Cardiac Radiofrequency Catheter Market
Despite the favorable macro outlook, the industry faces critical inflection points that demand strategic attention. First, the rapid adoption of pulsed field ablation (PFA) technologies is reshaping procedural workflows and device requirements, creating both opportunity and obsolescence risk for legacy systems. Second, reimbursement environments are evolving in complexity, with new coding structures for remote monitoring and digital health integration changing the economic calculus for hospitals and providers. Third, regulatory scrutiny is intensifying, particularly around safety labeling and real-world performance data, forcing manufacturers to balance speed-to-market with rigorous post-market surveillance. These challenges are not isolated; they interact to shape the pace of adoption and the allocation of capital across the value chain.
Key Drivers of Market Dynamics
Technological Innovation and Breakthroughs
The most conspicuous catalyst for market growth is the transition from thermal ablation modalities to non-thermal energy sources, particularly PFA. This shift promises shorter procedure times, reduced collateral tissue damage, and improved safety profiles, which in turn drive higher procedure volumes and broader patient eligibility. Mapping and navigation systems are also undergoing simultaneous refinement, with higher resolution, integration of artificial intelligence-assisted annotation, and seamless interoperability with imaging modalities. These advancements reduce operator dependency and standardize outcomes, making EP procedures more scalable across different care settings. The convergence of ablation precision and mapping fidelity is creating platforms rather than standalone devices, increasing the strategic value of integrated solutions.
Policy and Regulatory Environment
Regulatory frameworks are adapting to the pace of innovation while placing greater emphasis on procedural safety and post-market evidence. Recent updates to instructions for use for certain PFA systems, prompted by reviews of procedural adverse events, illustrate how regulators are tightening guidance without halting progression. Simultaneously, the expansion of indications for multiple PFA platforms through FDA approvals has broadened the addressable patient population, particularly for persistent forms of atrial fibrillation. This regulatory openness is contingent on robust clinical data and clear labeling, meaning that manufacturers with mature clinical programs and real-world evidence pipelines are better positioned to capitalize on indication expansions. Reimbursement policy is also evolving; newly introduced CPT codes for remote physiological monitoring and therapeutic services are aligning financial incentives with digital EP workflows, encouraging hospitals to invest in connected care infrastructure alongside hardware.
Cardiac Rhythm Management (CRM) Devices Market
Demand-Side Shifts in Provider and Patient Behavior
Healthcare providers are increasingly prioritizing efficiency, safety, and total cost of ownership over device price alone. As EP labs face capacity constraints and staffing pressures, solutions that reduce fluoroscopy time, shorten learning curves, and enable faster turnover are gaining preference. Patients, supported by greater awareness and improved screening, are seeking earlier intervention for arrhythmias, particularly atrial fibrillation, which remains the dominant application driving device utilization. The growing emphasis on minimally invasive approaches and outpatient procedural settings is also reshaping purchasing patterns, with institutions favoring platforms that support same-day discharge pathways and remote follow-up. These behavioral shifts reinforce the demand for integrated systems that deliver consistent clinical results across varied operator skill levels.
Supply Chain and Cost Structure Evolution
The supply chain for EP devices is under pressure from multiple directions. Component specialization, sterilization requirements, and regulatory-grade quality systems create inherent complexity, while geopolitical and logistics volatility have prompted manufacturers to diversify sourcing and increase inventory buffers for critical consumables. At the same time, the rise of reprocessing programs for certain diagnostic and mapping catheters introduces a parallel cost dynamic, offering institutions a way to manage expenditure on single-use items while navigating regulatory and quality assurance requirements. Cost containment efforts by providers are not necessarily negative for manufacturers; they can stimulate innovation in durable platforms, subscription-based software enhancements, and service models that convert capital expenditure into predictable operational costs. Companies that can articulate a compelling value proposition across the total cost of care are more likely to secure formulary placement and long-term contracts.
Competitive Landscape and Leading Strategies
Strategic Positioning of Leading Companies
The competitive field is anchored by a group of diversified medical technology companies that leverage broad commercial infrastructure, established physician relationships, and multi-product portfolios. Medtronic, headquartered in Minneapolis, offers a comprehensive EP portfolio that includes mapping and ablation systems for atrial fibrillation alongside defibrillation leads and cardiac ablation solutions. Its strategy emphasizes platform breadth and integration across the patient journey. Abbott, based in Abbott Park, combines EP ablation catheters with mapping tools and PFA systems, positioning around precision, workflow efficiency, and expanding clinical indications. Boston Scientific, in Marlborough, has gained attention with its PFA platform and mapping and ablation offerings, pursuing aggressive indication expansion and clinical evidence generation. Johnson & Johnson MedTech, through its electrophysiology business in Irvine, markets widely adopted mapping systems and PFA platforms, relying on brand recognition, extensive clinical networks, and continuous software advancement. Biotronik, from Berlin, focuses on ablation catheter families and PFA systems, differentiating through specialized therapy products and regional strength in European markets.
Beyond these scale players, the landscape includes technology specialists and novel entrants that target specific workflow gaps. Stereotaxis, in Saint Louis, develops robotically-navigated magnetic ablation catheters aimed at complex procedures, emphasizing precision and operator support in challenging anatomies. CoreMap is advancing a map-guided EP mapping system for atrial fibrillation ablation, with recent regulatory milestones supporting the expansion of clinical evaluation in the United States. Innovative Health operates as an FDA-cleared reprocessor of used EP devices, including mapping and diagnostic catheters, reflecting the growing institutional interest in cost management and sustainability. Each of these players contributes to a landscape that is simultaneously consolidating around platforms and fragmenting around specialized solutions.
Differentiation and Competitive Advantage
In a market where top firms hold a substantial share, differentiation is increasingly achieved through clinical evidence, workflow integration, and service ecosystems rather than hardware specifications alone. Companies that can demonstrate reduced complication rates, shorter procedure durations, and reproducible outcomes across varied operator experience levels are winning preference in high-volume centers. Software-enabled features, such as advanced annotation, procedural planning, and remote monitoring compatibility, are becoming strategic assets that enhance stickiness and create recurring value. Regulatory agility also matters; firms that efficiently navigate indication expansions and safety labeling updates can capture emerging patient populations before competitors solidify their position. Finally, commercial execution—training programs, field support, and reimbursement assistance—often determines the pace of adoption at the institutional level, making service and education as critical as product design.
Evolution of the Market Structure
The market is moving toward a hybrid structure. On one side, consolidation pressure exists as larger platforms absorb complementary technologies, expand indications, and bundle mapping with ablation to offer turnkey solutions. On the other side, differentiation and niche innovation persist, particularly in robotics, AI-assisted mapping, and cost-control services that address specific institutional needs. New entrants with focused clinical value propositions can gain traction if they solve acute workflow or safety problems, even in a concentrated market. The presence of reprocessing options further complicates the landscape by introducing cost arbitrage that incumbent manufacturers must acknowledge in their pricing and service strategies. Over time, the boundary between device, software, and service will continue to blur, rewarding organizations that can orchestrate multi-component solutions and sustain clinical credibility.
PW Consulting
Future Trends and Strategic Opportunities
Trend One: Platform Consolidation with Workflow-Centric Design
Over the next three to five years, EP procurement is likely to favor integrated platforms that unify mapping, ablation, and data management within a coherent workflow. Hospitals will increasingly evaluate total procedural efficiency rather than isolated device performance, favoring vendors that can reduce setup complexity, standardize annotation, and support remote follow-up. This trend creates opportunities for companies that invest in interoperability, training, and service integration, while posing risk for point solutions that cannot demonstrate additive value within a broader ecosystem. Strategic winners will be those that can show measurable improvements in lab throughput and operator consistency.
Trend Two: Expanded Indications and Broader Patient Access
The ongoing expansion of indications for PFA and advanced mapping systems is set to enlarge the treatable population, including patients with persistent atrial fibrillation and complex anatomies. As clinical evidence matures and labeling broadens, centers that previously deferred intervention may adopt earlier treatment strategies, increasing procedure volumes. This trajectory benefits manufacturers with robust clinical programs and clear safety narratives, but it also raises the bar for post-market data collection and Real-World Evidence. The opportunity lies in pairing indication expansion with education and reimbursement support, enabling providers to adopt new protocols confidently. The risk is that safety concerns or labeling updates could slow adoption if communication and training are inadequate.
Trend Three: Digital Integration and Value-Based Procurement
Digital health integration is becoming a competitive differentiator, with remote physiological monitoring and digital workflows gaining reimbursement support and clinical acceptance. Procurement decisions are increasingly influenced by total cost of care considerations, including readmission reduction, remote follow-up capability, and data analytics that inform population management. This environment rewards vendors that can connect device data to care pathways and demonstrate downstream economic benefits. At the same time, it introduces dependency on cybersecurity, data governance, and software lifecycle management. Organizations that treat software and services as first-class products, rather than add-ons, will be better positioned to align with value-based purchasing trends.
Actionable Recommendations for Decision Makers
For Manufacturers and Product Leaders
Prioritize platform coherence over incremental feature additions. Ensure that mapping, ablation, and software components share a unified workflow and that training, service, and reimbursement support are built into the commercial model. Invest in real-world evidence generation and proactive safety communication to navigate regulatory updates and sustain indication expansions. Where relevant, explore complementary capabilities such as remote monitoring integration or reprocessing-compatible designs to address total cost of care concerns without compromising clinical standards.
For Investors and Strategic Partners
Evaluate opportunities based on clinical differentiation, regulatory readiness, and the ability to integrate into hospital workflows rather than on technology novelty alone. Favor assets with clear paths to indication expansion, strong field support networks, and defensible data assets. Pay attention to the reprocessing segment and digital monitoring services as adjacent areas that can influence device economics and adoption patterns. Diversification across platform plays and focused workflow solutions can balance scale potential with niche growth.
For Procurement and Clinical Operations Leaders
Structure evaluation criteria around total procedural efficiency, safety consistency, and long-term service support, not solely on unit pricing. Demand evidence of workflow reduction, learning curve mitigation, and compatibility with remote monitoring where applicable. Negotiate for training, data integration, and reimbursement assistance as part of the purchasing package. Consider hybrid sourcing strategies that balance platform reliability with cost-control mechanisms, while ensuring that quality and regulatory compliance remain non-negotiable.
The electrophysiology device market is at a intersection of technological momentum, regulatory evolution, and changing economic incentives. For leaders navigating this environment, timely and granular intelligence is essential to distinguish durable trends from transient noise. Detailed segmentation data, competitive drills, and tailored scenario analysis can sharpen strategic choices and reduce execution risk. For those seeking a deeper, more customized view of the market—including segment-level dynamics, regional nuances, and actionable growth pathways—accessing a comprehensive research report can provide the granularity needed to move from insight to implementation.
For detailed analysis of this topic, please visit the official page: Electrophysiology (EP) Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Bench-top Sterilizer Market at a Crossroads: Strategic Trends and Commercial Opportunities
The bench-top sterilizer market has settled into a phase of steady, predictable growth that masks significant underlying shifts. Over the 2020–2025 period, the sector expanded from a modest base to a revenue run rate approaching $237 million (USD), driven by incremental adoption across healthcare, dental, and laboratory environments. Forward projections through 2032 point to a compound annual growth rate of roughly 4.5%, with the market expected to surpass $320 million by the end of the decade. These figures describe continuity, but they also reveal a market that is being quietly reshaped by regulatory clarity, technology modularization, and structural changes in how small-to-mid-sized care and research facilities manage infection control and workflow efficiency.
For executives and investors, the headline growth rate is less important than what is driving it and where friction points are emerging. The bench-top sterilizer segment is no longer a commodity-adjacent category defined by basic steam cycles and price competition. It is becoming a differentiated equipment niche where software upgradeability, water and utility integration, compliance rigor, and space-constrained design are separating capable suppliers from the rest. At the same time, reimbursement structures and procurement behaviors are placing new emphasis on total cost of ownership and demonstrable compliance, which means that competitive advantage will increasingly come from ecosystem thinking rather than instrument-level specifications alone.
Market Snapshot and the Shape of Growth
The market's trajectory from 2020 through 2025 reflects a recovery and stabilization pattern after the volatility introduced by pandemic-era procurement. Revenue climbed through 2023, experienced a modest contraction in 2024, and then resumed growth in 2025 as facilities normalized capital equipment refresh cycles. This sequence matters because it indicates that demand is not purely cyclical; it is being reinforced by longer-term factors such as the expansion of outpatient procedures, the proliferation of dental service organizations, and the ongoing modernization of laboratory infrastructure in both academic and commercial settings.
Concentration in the market remains moderate. The top three players collectively hold around 28% of revenue, and the top five account for approximately 32.5%. This level of fragmentation suggests that no single supplier has achieved dominance through scale alone. Instead, the market rewards specialization by end-use environment, regulatory readiness, and regional service capabilities. For new entrants and incumbents alike, this is a critical structural insight: broad portfolios do not automatically win, but targeted positioning against specific user profiles—dental clinics, small hospital outpatient units, research labs, and decentralized care sites—can build defensible niches.
The growth outlook through 2032 implies that the market will add meaningful volume without experiencing a step-change explosion. That kind of trajectory is attractive for operators that can manage yield, service economics, and regulatory compliance efficiently, but it also raises the bar for differentiation. When growth is moderate, margin protection and customer retention become the primary value-creation mechanisms.
Core Challenges and Inflection Points
Three interconnected challenges are defining the current inflection point for bench-top sterilizers. First, compliance expectations are becoming more granular and more auditable. Users in medical and dental environments are operating under standards that require not just functional sterilization performance but documented process reliability, cycle validation, and equipment upgrade paths that maintain classification integrity. This shifts purchasing criteria from initial purchase price toward lifecycle compliance assurance, which can disadvantage suppliers whose products are difficult to upgrade or whose documentation and service models are less rigorous.
Second, space and utility constraints are intensifying. Many dental offices, outpatient clinics, and research laboratories operate in facilities where floor space, plumbing, and power capacity are limited. Bench-top devices are inherently appealing in these settings, but they also create hidden operational dependencies. Water quality, drainage, and ambient conditions can affect sterilization reliability and service frequency. Suppliers that ignore the auxiliary infrastructure required to run bench-top sterilizers effectively risk higher callback rates and weaker customer satisfaction, even when the sterilizer itself performs well.
Third, reimbursement and procurement dynamics are reshaping the economics of adoption. In hospital outpatient settings, payment frameworks continue to recognize device pass-through mechanisms, but the absence of sterilizer-specific add-ons means that facilities weigh these purchases against broader budget pressures and operational priorities. For dental and laboratory buyers, the decision calculus is often more fragmented and discretionary, influenced by local service availability, training burden, and perceived risk. The practical effect is that the market does not respond uniformly to macro tailwinds; it responds to whether suppliers can translate clinical and operational value into lower friction for the buyer.
Key Drivers Reshaping Demand and Competition
Technology modularization is one of the most consequential drivers in the segment. Rather than forcing buyers to choose a fixed configuration at purchase, some manufacturers are enabling software-driven upgrades that move equipment between classification levels or unlock additional cycle capabilities. This approach aligns with the way many clinics and labs actually operate: they often start with a narrower use case and expand later, or they need flexibility to handle different instrument loads without acquiring separate units. Modular upgradeability also helps mitigate the risk of obsolescence in a market where purchasing cycles can be long and budgets constrained.
Regulatory alignment is another powerful driver. Products that are designed around recognized sterilization standards and that carry appropriate clearances for reusable medical devices reduce the burden on facilities to justify compliance internally. In environments where infection control audits, accreditation visits, and risk management reviews are frequent, documented conformity is not a minor convenience; it is a procurement prerequisite. Equipment that can demonstrate adherence to applicable performance and validation expectations gains trust faster and tends to encounter fewer barriers during purchasing and inspection cycles.
PW Consulting
Demand-side behavior is shifting toward integrated workflow thinking. Dental service organizations, outpatient providers, and laboratory managers increasingly evaluate sterilization equipment not as an isolated instrument but as part of a compact clinical or research process. That perspective favors solutions that are compact without being compromised, intuitive to operate, and supported by service and training models that minimize downtime. It also increases the importance of auxiliary systems that support sterilizer performance, such as purified water delivery, because reliability at the point of use often depends on more than the sterilizer cabinet itself.
Supply chain and cost structure considerations remain relevant, particularly for suppliers operating across multiple geographies. Raw material volatility, production consistency, and the cost of maintaining regional service networks all influence margin outcomes. But in this mature-yet-evolving market, the more decisive cost lever is often operational rather than manufacturing alone. Reducing installation friction, simplifying maintenance, and lowering the total cost of ownership through reliable performance and predictable service intervals can be more impactful than marginal reductions in unit price.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of established Western manufacturers with strong clinical and dental heritage and smaller specialized players focused on laboratory and research-grade applications. Companies such as Tuttnauer, Midmark Corporation, and MELAG Medizintechnik have built reputations around steam and hot air sterilization solutions tailored to healthcare and dental settings. Their strategic positioning tends to emphasize compliance readiness, cycle reliability, and product lines that address the everyday operational realities of clinical environments. In a market where end users value familiarity, service accessibility, and auditable performance, these strengths can translate into durable customer relationships.
On the laboratory and research side, suppliers including Consolidated Sterilizer Systems, Priorclave, D.A.I. Scientific, and Benchmark Scientific focus on compact, application-specific bench-top units that serve space-constrained and specialized workflows. Their differentiation often lies in research-grade construction, practical ergonomics, and support structures that match laboratory usage patterns. Meanwhile, manufacturers like Scitek Global illustrate the growing role of ISO 13485-aligned production and Class B vacuum bench-top designs in expanding the field's quality expectations and geographic reach. This mix suggests that the market is not converging on a single template; it is supporting multiple viable value propositions as long as each is clearly tied to a defined user environment.
Recent company-level developments highlight the directions that forward-looking suppliers are taking. One notable example is the recognition of certain bench-top autoclaves through a technology breakthrough designation, accompanied by the ability to upgrade from Class S to Class B through a software update. This combination matters because it links innovation credibility with practical flexibility, allowing facilities to preserve capital while expanding capability. It also underscores a broader shift in which software is becoming a strategic layer in sterilization equipment, not merely a control interface.
Another meaningful development is the introduction of compact wall-mounted water purification systems designed to support bench-top sterilizer operations in healthcare and life science laboratories. This Signals an important evolution in how suppliers think about the sterilizer ecosystem. When purified water delivery is engineered as a complementary system, it addresses a real operational dependency and reduces the risk of performance variability. It also opens the door to more integrated commercial models, where suppliers can offer bundled solutions that improve reliability and simplify installation for end users.
Plasma Sterilizers Market
The market is likely to continue evolving through a combination of incremental consolidation and targeted expansion. Moderate concentration leaves room for bolt-on acquisitions, especially where a larger player can add geographic coverage, service density, or a complementary product line. At the same time, new entrants can still succeed by attacking specific pain points—space limitations, water infrastructure, upgradeability, or compliance documentation—if they avoid direct confrontation with entrenched incumbents in broad, undifferentiated segments.
Looking Ahead: Three Trends Shaping the Next Three to Five Years
Software-defined flexibility will become more central to commercial positioning. As more buyers seek to future-proof limited capital budgets, the ability to reconfigure performance through updates rather than hardware replacement will be increasingly valued. This trend favors suppliers that can manage software lifecycle responsibilities, validate upgrade paths, and communicate the compliance implications clearly. It also raises the stakes for post-sale support, because software-driven capability changes must be paired with training and documentation that keep users confident and audit-ready.
Integrated utility and purification support will move from niche convenience toward a more standard expectation in many deployment scenarios. Bench-top sterilizers are attractive partly because they reduce footprint, but their performance and service reliability often depend on water quality and installation conditions. Suppliers that offer or partner for supporting water purification, simplify plumbing requirements, or design for easier integration into constrained spaces will have an advantage in environments where facilities lack dedicated infrastructure teams. The commercial implication is that equipment sales may increasingly be accompanied by accessory systems, service agreements, and installation guidance that collectively lower risk for the buyer.
Regulatory and compliance maturity will continue to reward manufacturers that treat conformity as a product attribute rather than a paperwork exercise. The more clearly equipment aligns with recognized sterilization expectations and carries appropriate clearances for intended uses, the easier it becomes for facilities to adopt it and defend the decision internally. In parallel, reimbursement and payment dynamics will keep encouraging buyers to focus on value that reduces operational friction, since device-specific reimbursement remains limited. Together, these forces will push the market toward solutions that combine credible compliance, practical usability, and lower hidden costs over the equipment lifecycle.
These trends create commercial opportunities for manufacturers that can articulate a clear end-use fit, for investors that can identify suppliers with strong service economics and defensible niches, and for procurement teams that can prioritize total cost of ownership and compliance confidence over initial price. The principal risk is complacency among suppliers that assume moderate market growth will protect them from competitive pressure. In a fragmented market with rising expectations, the winners are likely to be those that invest in differentiation where it matters most to the buyer: flexibility, reliability, and support.
Actionable Implications for Decision Makers
Manufacturers should prioritize modularity and ecosystem readiness over breadth alone. The ability to upgrade configurations through software, support compliant use across intended applications, and address auxiliary needs such as water quality can be more differentiating than expanding the number of models in a catalog. Equally important is the service model: predictable maintenance, rapid local support, and clear documentation will increasingly determine whether a purchase becomes a long-term relationship or a short-lived deployment.
Investors should evaluate not only unit sales momentum but also the quality of customer retention and the economics of downstream support. In a market growing at a moderate pace, durable value often depends on repeat service revenue, low callback rates, and the ability to cross-sell complementary systems that improve reliability. Suppliers that can demonstrate a repeatable operating model across dental, medical, and laboratory segments—without diluting their focus—may offer more resilient exposure than those relying on broad but shallow product lines.
Procurement and operations leaders should evaluate bench-top sterilizers as part of a compact workflow rather than as standalone instruments. That means validating compliance documentation, confirming the practical requirements for installation and water quality, and assessing how easily the unit can adapt if the facility's mix of instruments or sterilization needs changes over time. A lower purchase price can be outweighed by hidden costs in service frequency, training burden, or operational constraints, especially in space-limited environments.
For organizations that need to pressure-test a specific market entry, portfolio extension, or procurement decision, the full set of segmentation detail, competitive profiles, and scenario analysis can be critical. PW Consulting's complete research report on the bench-top sterilizer market provides deeper breakdowns and tailored recommendations for manufacturers, investors, and buying organizations seeking to act with greater precision.
The bench-top sterilizer market is not experiencing a dramatic disruption, but it is undergoing a meaningful re-pricing of what creates value. Compliance clarity, software-enabled flexibility, utility integration, and service reliability are becoming the anchors of competitive advantage. For leaders willing to look beyond the headline growth figures, the opportunity lies in aligning product strategy and purchasing decisions with the way end users actually operate—where space is tight, workflows are compact, and confidence in sterilization performance is non-negotiable.
Sterilization Equipment Market
For detailed analysis of this topic, please visit the official page: Bench-top Sterilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Pressure Cooker Market: Why Asia Pacific’s Scale Drives 2.9% CAGR Growth Through 2032
By pmarketresearch, 2026-09-21
Electric Pressure Cooker Market: Strategic Trends and Commercial Opportunities Through 2032
The electric pressure cooker market has transitioned from a niche kitchen accessory to a mainstream appliance category, driven by shifting consumer habits, technological maturation, and evolving regulatory expectations. From a base valuation of approximately 4.5 billion USD in 2020, the market has expanded to an estimated 5.2 billion USD by 2025, reflecting a compound annual growth rate of 2.9 percent over the historical period. Looking ahead to 2032, the sector is projected to reach 6.45 billion USD, with growth pacing itself around the mid-single-digit range. These figures signal a market that has moved past its initial adoption curve and is now entering a phase where differentiation, compliance, and operational efficiency determine competitive positioning rather than mere product availability.
For executives and investors, the numbers alone do not capture the underlying dynamics. The market is consolidating around established players while simultaneously opening doors for brands that can deliver smarter functionality, tighter safety standards, and region-specific go-to-market strategies. The following analysis unpacks the structural forces shaping the category, the competitive maneuvers defining leadership, and the strategic decisions that will separate resilient operators from those caught off guard by regulatory or demand-side shifts.
Market Snapshot and Structural Challenges
The 2026–2032 forecast window indicates a market that will continue to grow but at a measured pace. The 2.9 percent CAGR suggests steady expansion rather than explosive adoption, reflecting a category that has achieved broad baseline penetration in several mature markets while still facing headroom in others. Revenue distribution across regions, product types, and end-use segments reveals a landscape where Asia Pacific commands the largest share of activity, followed by North America and Europe, with Latin America and the Middle East and Africa representing smaller but strategically relevant pockets. The split between mechanical timer and digital/programming variants shows a near-even divide, indicating that affordability and simplicity still compete effectively against feature-rich smart appliances. Residential applications dominate commercial use by a wide margin, reinforcing the consumer-oriented nature of the category even as foodservice and institutional channels contribute a meaningful secondary demand stream.
Within this framework, three structural challenges stand out as critical inflection points for the next cycle.
Multi-Functional Cooking Food Processors Market
Safety Compliance and Recall Exposure
Product safety has emerged as a defining constraint. The category relies on pressurized cooking environments, and any failure in lid locking, pressure release, or thermal management can result in burn injuries and rapid regulatory intervention. High-profile recalls of multi-function pressure cookers and electric pressure cooker units have highlighted how quickly reputational risk can escalate when safety engineering lags behind feature proliferation. For manufacturers, this means that compliance is no longer a backend cost center but a front-line differentiator. Brands that can demonstrate rigorous validation, transparent failure-mode analysis, and responsive field action protocols will be better positioned to retain consumer trust and avoid costly inventory write-downs.
Feature Saturation and Value Perception
As digital programming, app connectivity, and multi-cooker hybrids become more common, the market risks diluting perceived value. Consumers and procurement teams increasingly evaluate whether added complexity translates into measurable convenience, energy savings, or cooking consistency. When premium features do not deliver clear usability benefits, price sensitivity rises and mid-tier mechanical alternatives regain traction. The challenge for brands is to avoid feature bloat while still offering enough differentiation to justify premium positioning. Investment in intuitive interfaces, reliable pressure control, and clear cooking presets often yields stronger returns than expanding technological specifications without user-centric design.
Regional Divergence in Adoption and Cost Structures
The market does not move uniformly across geographies. In higher-income regions, demand is shaped by convenience-driven meal preparation, brand loyalty, and a willingness to pay for smart functionality. In price-sensitive markets, volume growth depends on accessible pricing, durability, and distribution reach. Supply chain localization, component sourcing, and after-sales service expectations vary accordingly. A strategy that works in one region can underperform in another if it fails to align with local purchasing behavior, electrical standards, or competitive density. This divergence forces manufacturers and investors to think in terms of regional playbooks rather than a single global rollout.
Key Demand Drivers and Structural Shifts
The market's trajectory is being shaped by interconnected forces that touch technology, policy, consumer behavior, and supply-side economics. Understanding how these drivers reinforce one another provides a clearer view of where commercial opportunity is forming.
Technology Innovation and Smart Cooking Convergence
Technological progress in electric pressure cookers has moved beyond basic pressure maintenance toward integrated cooking logic. Digital controllers, timed presets, and adaptive heating elements are improving repeatability and reducing user error. The convergence of pressure cooking with slow cooking, sautéing, and keeping-warm functions has expanded the appliance's role in everyday meal preparation. More importantly, the push toward smarter operation is shifting competitive emphasis from hardware alone to software-defined experiences. Brands that can deliver consistent cooking outcomes, easy cleaning, and predictable energy use are gaining an edge in households where time and reliability matter more than raw specifications.
Policy, Standards, and Safety Accountability
Regulatory scrutiny is intensifying around pressure appliance safety, lid integrity, and thermal protection. Public recalls and injury reports have reinforced the expectation that manufacturers must design for fail-safe operation and maintain traceable quality controls. This environment favors companies that invest early in compliance engineering, third-party testing, and post-market monitoring. It also creates a barrier to entry for lower-cost players that cannot sustain the overhead of robust safety validation. Over time, the policy environment is likely to reward brands that treat safety as a product architecture principle rather than a reactive checklist, turning compliance into a credibility asset.
Demand-Side Behavior and Lifestyle Compression
Consumer behavior continues to favor appliances that reduce active cooking time without sacrificing meal quality. Busy household schedules, interest in healthier cooking methods, and a broader acceptance of one-pot meal preparation all support demand for electric pressure cookers. At the same time, consumers are becoming more selective about total cost of ownership, including durability, replacement part availability, and energy consumption. Commercial users, while smaller in volume, are influenced by labor efficiency, batch consistency, and equipment footprint. In both residential and commercial settings, the value proposition is increasingly tied to predictability: users want appliances that deliver the same result with minimal supervision.
Supply Chain, Manufacturing, and Cost Structure
The competitive economics of the market are influenced by component availability, manufacturing scale, and the balance between proprietary design and outsourced production. Large manufacturers with vertical integration or established OEM relationships can manage cost volatility more effectively and adjust output in response to demand fluctuations. Meanwhile, brands that rely on external suppliers must navigate pricing pressure, lead-time variability, and quality consistency. Regional manufacturing footprints also matter because they affect shipping costs, tariff exposure, and speed to market. Companies that can align production capacity with regional demand patterns while maintaining strict quality gates are better positioned to protect margins through the forecast period.
Competitive Landscape and Leadership Strategies
The market is characterized by a concentrated core of established brands alongside a long tail of regional and specialty players. Top-tier players collectively hold a significant share of revenue, with concentration levels indicating that a handful of names account for a large portion of industry activity. This structure rewards scale, brand equity, distribution reach, and the ability to manage safety and quality at volume.
Strategic Positioning Among Leading Companies
Several companies illustrate the different routes to competitive advantage in this category. Instant Brands Inc. has built strong recognition through a focused lineup of electric pressure cookers and multi-cookers, emphasizing user-friendly cooking programs and broad consumer awareness. SEB Group leverages a portfolio that includes well-known pressure cooker labels and a long heritage in kitchen appliances, using brand trust and multi-market presence to sustain relevance. Midea Group combines its own branded offerings with OEM capabilities, giving it flexibility to serve both direct consumer channels and behind-the-brand manufacturing demand. National Presto Industries, Inc. maintains a legacy-oriented approach centered on dependable electric pressure cookers, appealing to buyers who prioritize proven design and straightforward operation. Breville Group positions itself around performance-oriented appliances, targeting users who value precision cooking and higher-end build quality.
The competitive field also includes brands that have grown by emphasizing specific product experiences or channel strengths. Ninja, operating under SharkNinja, has expanded its footprint with multi-function pressure cookers that blend pressure cooking with other modes, gaining traction through aggressive product iteration and retail presence. Cosori has focused on electric pressure cookers with an emphasis on accessible design and digital features. Fissler brings a European engineering perspective through its pressure cooker lines, appealing to markets that value durability and cooking performance. Galanz Group and Joyoung Co., Ltd. reflect the importance of manufacturing scale and regional demand leadership, with product lines and OEM activity that support both consumer markets and broader appliance ecosystems.
PW Consulting Health Care Research Center
Differentiation Through Safety, Experience, and Channel Control
Across these players, the most durable differentiators are converging around three themes. First, safety engineering and transparent quality processes are becoming a license to operate in high-visibility markets. Second, user experience matters as much as hardware, with interface clarity, preset reliability, and ease of cleaning influencing repeat purchase and recommendation. Third, channel strategy remains critical because retail partnerships, e-commerce visibility, and service networks shape both reach and brand perception. Companies that align product design with safety expectations, then reinforce that alignment through controlled distribution and responsive support, are creating a more resilient competitive position.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The landscape is likely to evolve through a combination of consolidation among mid-tier players and continued fragmentation in regional niches. Larger brands may pursue acquisitions, channel expansion, or product line extensions to strengthen scale and geographic coverage. At the same time, smaller entrants can find room in specialized segments, such as compact appliances, design-forward products, or region-specific pricing tiers. However, the safety and compliance environment raises the cost of entry, meaning new players must prove reliability quickly to avoid regulatory setbacks and reputational damage. The result is a market where scale and discipline increasingly matter, but where targeted innovation can still open defensible positions if supported by strong quality controls.
Forward Outlook: Trends and Commercial Implications
Looking toward the late 2020s and into 2032, three trends are likely to shape the market's next phase and create distinct commercial implications.
Safety-First Product Architecture Becomes Table Stakes
The pattern of recalls and injury reports is pushing the category toward a safety-first design culture. Expect greater emphasis on lid-lock verification, pressure-release reliability, thermal safeguards, and clearer user feedback during operation. For manufacturers, this trend creates an opportunity to build brand credibility by making safety features visible and understandable rather than hidden inside the product. For investors, it signals that margin models dependent on cutting corners in validation or materials will face growing risk. The commercial opportunity lies in brands that can communicate dependable performance without overpromising, and that can maintain rigorous post-sale monitoring to manage issues before they scale.
Smart Functionality With Practical Value Wins Over Feature Proliferation
Digital and programming segments are expected to continue gaining ground, but the winning products will be those that connect technology to everyday usefulness. Appliances that offer reliable presets, consistent results, and easy operation will outperform those that add connectivity without solving real user pain points. This trend favors companies that invest in software usability, recipe-driven guidance, and maintenance reminders that extend product life. It also creates an opening for brands to differentiate through ecosystem integration, such as coordinated cooking workflows or compatibility with broader kitchen routines, provided those features genuinely reduce effort rather than complicate it.
Regional Playbooks Will Determine Growth Quality
As the market matures, growth quality will depend less on blanket global expansion and more on region-specific execution. In higher-income markets, premiumization and smart features may drive mix improvement. In price-sensitive markets, volume will depend on accessible pricing, durable construction, and distribution density. In commercial segments, demand will hinge on labor savings, throughput consistency, and service reliability. Companies that tailor product specifications, pricing, and after-sales support to local expectations will be better positioned to convert market growth into sustainable share gains. The risk is that brands relying on a single product strategy across all regions will face margin compression or missed adoption windows.
Risk and Uncertainty to Monitor
Several uncertainties could alter the pace or shape of growth. Regulatory actions may become more stringent if safety incidents continue to draw attention, raising compliance costs and slowing product launches. Supply chain disruptions or component shortages could pressure pricing and availability, especially for brands with limited manufacturing flexibility. Consumer sentiment may shift if economic pressures reduce discretionary spending on premium appliances, making value-oriented alternatives more attractive. Finally, the pace of smart-feature adoption could disappoint if users perceive limited benefit relative to cost, prompting a reversion toward simpler mechanical options in certain segments. Monitoring these signals will be essential for anticipating shifts in demand mix and competitive intensity.
Actionable Priorities for Decision Makers
The commercial path forward depends on how companies align product strategy, compliance culture, and regional execution. The following priorities can help translate market dynamics into practical decisions.
Stainless Steel Cookware Market
For Manufacturers and Brand Owners
- Treat safety engineering as a core design parameter, not a post-development review. Build validation, lid-lock reliability, and pressure management into product architecture early, and document failure-mode controls in a way that supports both compliance and consumer confidence.
- Balance feature sets with usability. Prioritize digital functions that improve repeatability, reduce supervision, and simplify cleanup. Avoid adding complexity that does not translate into a tangible user benefit, because value perception will increasingly determine willingness to pay.
- Align production and distribution with regional demand profiles. Consider where scale, OEM relationships, local assembly, or channel partnerships provide the strongest advantage, and avoid assuming that a single product formula will perform uniformly across markets.
For Investors and Strategic Planners
- Focus on companies with credible safety practices, disciplined cost structures, and clear brand positioning. In a market where recalls can rapidly reshape reputation, operational discipline is a meaningful indicator of resilience.
- Evaluate growth by segment and region rather than relying on aggregate market size alone. Revenue opportunities differ across residential and commercial use, across mechanical and digital types, and across geographies with very different purchasing behavior.
- Watch for consolidation signals among mid-tier players and for new entrants that can demonstrate both innovation and compliance capability. M&A, channel partnerships, and OEM relationships will likely shape competitive positioning as the market matures.
For Procurement, Retail, and Commercial Buyers
- Assess suppliers on total reliability rather than sticker price alone. Lid integrity, pressure control consistency, service support, and replacement part availability can affect downstream risk and user satisfaction more than initial purchase cost.
- Include safety documentation, recall history, and post-market response in vendor evaluation. A supplier's willingness to maintain transparent quality processes is a practical indicator of long-term partnership value.
- Match product selection to end-user expectations. Residential buyers may prioritize ease of use and preset reliability, while commercial operators may value throughput, durability, and service responsiveness. Aligning assortment with actual usage improves adoption and reduces returns.
The electric pressure cooker market is entering a phase where disciplined execution matters more than raw expansion. Growth will continue through 2032, but the companies that convert that growth into durable advantage will be those that treat safety, usability, and regional fit as strategic imperatives. Detailed segmentation data, competitive benchmarking, and scenario-based planning can help translate these broader trends into specific decisions for product roadmap, market entry, and investment allocation. For decision makers seeking a deeper dive into segment-level dynamics and tailored guidance, the full research report provides the more granular view needed to move from market understanding to action.
For detailed analysis of this topic, please visit the official page: Electric Pressure Cooker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Online Accounting Software Market: Why a 9.6% CAGR and SaaS Shift Change Everything
By pmarketresearch, 2026-09-21
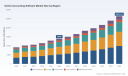
The $26 Billion Horizon: Strategic Shifts in the Online Accounting Software Market
The global online accounting software market has matured into a foundational digital infrastructure for enterprises of every scale. With revenue surpassing $14 billion in 2025 and a projected expansion to approximately $26.4 billion by 2032, the sector is advancing at a compound annual growth rate of 9.6 percent. This trajectory reflects more than routine digitization; it signals a structural realignment in how firms capture, reconcile, and act upon financial data. As cloud-native platforms replace legacy on-premise systems, accounting software is increasingly functioning as the operational core of broader enterprise technology stacks. For executives, strategists, and investors, the critical question is no longer whether to adopt online accounting solutions, but how to navigate the compounding technological, regulatory, and competitive dynamics that will determine market positioning over the next half decade.
Despite the favorable growth trajectory, the industry confronts several structural friction points that are reshaping vendor roadmaps, customer purchasing behavior, and capital allocation strategies. First, legacy migration and process standardization remain persistent barriers. Organizations still operating fragmented spreadsheets, outdated desktop packages, or heavily customized ERPs face steep integration and training costs. The perceived risk of operational disruption often delays adoption, even when long-term efficiency gains are clear. Second, the accounting talent bottleneck is intensifying. As platforms automate data entry, reconciliation, and reporting, firms are demanding higher-order analytical and advisory capabilities from finance teams, yet the pipeline of professionals skilled in both financial operations and digital tooling remains constrained. Third, the post-pandemic normalization of remote and hybrid work models has altered procurement expectations. Decision-makers now prioritize seamless cross-device access, real-time collaboration, and integration with geographically distributed banking and payment ecosystems. These pressures are not merely operational; they are redefining vendor selection criteria and accelerating the shift from point-solution purchasing toward unified, workflow-aware platforms.
Market authorities, vendor product cycles, and macroeconomic indicators point to a clear inflection point. Cloud accounting is no longer a convenience layer; it is becoming the data spine for treasury management, compliance automation, and strategic decision-making. The firms that will capture disproportionate value are those that align platform capabilities with these evolving operational realities rather than simply replicating traditional bookkeeping functions in a browser.
Key Drivers Reshaping the Market
Technology Innovation and the Automation Ceiling
The most consequential driver in the online accounting software space is the rapid integration of artificial intelligence and machine learning into core financial workflows. Early automation focused on rule-based transaction categorization and recurring invoice generation. Contemporary platforms are advancing toward intelligent reconciliation, contextual anomaly detection, and narrative financial summarization. Vendors are embedding AI-assisted bookkeeping, predictive cash flow modeling, and automated audit trail generation directly into cloud environments. The operational impact is substantial: finance teams are reducing manual review cycles, lowering error rates in high-volume transaction processing, and freeing capacity for scenario planning and working capital optimization. For mid-market and enterprise buyers, the value proposition has shifted from basic digitization to continuous, low-friction financial intelligence.
This shift is already visible in product development cycles across the ecosystem. Platform updates from major providers increasingly emphasize generative capabilities for report drafting, intelligent receipt and invoice matching, and natural-language query interfaces. The underlying trend is a gradual erosion of the traditional boundary between accounting software and broader financial operations platforms. As AI handling of routine tasks reaches higher accuracy thresholds, vendors are reallocating engineering resources toward workflow orchestration, multi-entity consolidation, and real-time decision support. Providers that treat automation as a standalone feature rather than an integrated capability risk commoditization, while those that embed it into end-to-end processes are building defensible switching costs.
Accounting Software Market
Regulatory and Data Infrastructure Pressures
The regulatory and infrastructure environment is exerting a quieter but increasingly material influence on cloud accounting deployment. Data sovereignty requirements, cross-border reporting mandates, and evolving audit expectations are pushing vendors to invest in regional compliance frameworks and localized data handling options. Simultaneously, the physical and economic realities of cloud infrastructure are entering strategic conversations. Hyperscale data center demand driven by AI and cloud workloads is projected to more than double by the end of the decade, raising compute and storage costs that eventually cascade into software pricing, tier structures, and service-level commitments. In several U.S. jurisdictions, state-level returns on data center investments have fallen materially short of projections, prompting stricter permitting, sustainability reviews, and community-level scrutiny. Multiple large-scale facilities faced delays or denials in recent periods, and a significant volume of infrastructure capital remains stalled in permitting pipelines.
These dynamics carry direct implications for online accounting providers. Vendors dependent on centralized hyperscale environments may face capacity constraints, latency trade-offs, or cost pressures that affect scalability and deployment timelines. For enterprise buyers, this translates into a more complex evaluation matrix that now includes provider infrastructure resilience, data residency options, and long-term pricing stability. The regulatory and infrastructure conversation is no longer a back-office concern; it is becoming a factor in vendor selection, contract structuring, and multi-year technology planning.
Demand-Side Shifts and the Rise of Platform Ecosystems
Customer expectations are evolving faster than the traditional accounting software catalog. Small and mid-sized businesses increasingly view financial tooling not as isolated bookkeeping systems but as integrated components of broader operational workflows that span invoicing, payroll, inventory, CRM, banking, and payment processing. Large enterprises, meanwhile, are prioritizing consolidation, advanced multi-entity reporting, subscription billing, and alignment with existing ERP and treasury environments. In both segments, procurement decisions are being driven by interoperability, user experience, and the ability to reduce context-switching across tools. Buyers are less willing to accept rigid, standalone packages and more inclined toward modular ecosystems that can scale with organizational complexity.
This demand evolution is reshaping competitive positioning. Vendors that originally built value propositions around specific audience segments are expanding their functional footprints, while broader technology and financial services players are entering the accounting workflow space through partnerships, embedded finance products, or integrated platform suites. The result is a marketplace where differentiation increasingly depends on integration breadth, workflow customization, and the depth of domain-specific automation rather than basic cloud availability.
Competitive Landscape and Strategic Positioning
Divergent Models Among Established Leaders
Intuit maintains a strong foothold through cloud accounting platforms tailored to small and mid-sized businesses, emphasizing AI-assisted bookkeeping, invoicing, and real-time financial visibility. Its strategic emphasis has been on embedding accounting within a broader small-business ecosystem, reducing friction in everyday financial operations, and expanding the addressable use case beyond traditional ledger management. Xero has cultivated a distinct position by prioritizing real-time bank synchronization, workflow automation, and multi-currency capabilities for small to mid-sized firms. Its differentiation rests on open integration architectures and a partner network that extends platform functionality across geographies and verticals. Sage continues to focus on mid-market and enterprise complexity, offering cloud ERP and accounting solutions with advanced financial consolidation, subscription billing, and multi-entity governance. Its trajectory reflects a push toward higher-value financial management rather than transactional bookkeeping alone.
Wave and FreshBooks illustrate another strategic axis: highly segmented, user-centric solutions for freelancers, service businesses, and early-stage companies. Their emphasis on free or low-friction entry points, time tracking, expense management, and simplified invoicing demonstrates how specialized positioning can sustain growth in crowded segments by reducing adoption barriers and aligning tightly with specific workflow patterns. Zoho Books reflects the broader platform-play approach, bundling accounting with automation and cross-application interoperability for small businesses and startups, leveraging ecosystem scale to offer extensive user capacity and integrated process flow.
Recent events underscore the intensity of this competitive recalibration. In early 2025, a major provider expanded its North American presence with a new headquarters designed to accelerate cloud accounting growth and client collaboration. Later in the year, a newer entrant introduced an AI-enabled accounting agent for cloud environments, reporting high accuracy in reconciliations and receipt matching. A workflow specialist released a cloud-based practice management tool aimed at accounting firms, targeting client communication and internal process coordination. Meanwhile, a large enterprise cloud provider embedded a generative AI assistant capable of drafting financial reports and narrative summaries, and a commercial bank launched an integrated cloud accounting platform connecting banking services directly to bookkeeping for enterprise clients. These moves are not isolated product launches; they signal converging strategies around AI capability depth, workflow orchestration, and ecosystem integration.
Consolidation, Fragmentation, and New Entry Dynamics
The market is simultaneously exhibiting consolidation and differentiation. Larger players are pursuing broader functional coverage, deeper enterprise features, and strategic partnerships that extend reach into banking, payroll, and practice management. At the same time, specialized solutions continue to thrive by occupying narrow segments with superior user experience, rapid deployment, or vertical-specific automation. New entrants are emerging around AI-native reconciliation, automated compliance support, and embedded financial services, often competing on accuracy, speed, and workflow simplicity rather than legacy feature breadth.
Market concentration remains moderate, with a limited number of large vendors commanding a meaningful share of revenue while a long tail of niche and regional providers competes on service quality, localization, and integration depth. This structure suggests that competitive advantage will increasingly derive from execution quality, ecosystem relationships, and the ability to reduce total cost of ownership across the finance function rather than from proprietary ledger technology alone. For buyers, the implication is a more dynamic evaluation environment in which switching costs, integration commitments, and long-term roadmap alignment matter as much as current feature sets.
Outlook: Three Trends Shaping the Next Three to Five Years
From Bookkeeping to Continuous Financial Operations
Over the next several years, online accounting software is likely to be evaluated less as a record-keeping tool and more as a continuous financial operations layer. AI-driven reconciliation, anomaly detection, and automated reporting will become baseline expectations rather than premium differentiators. Platforms that can synthesize transactional data, banking flows, and operational inputs into forward-looking insights will gain preference in both mid-market and enterprise segments. This shift creates opportunities for vendors to expand into working capital optimization, scenario modeling, and advisory-adjacent workflows. It also raises the stakes for providers that remain anchored in retrospective accounting functions, as customers increasingly expect systems that support both compliance and decision velocity.
A persistent risk in this trajectory is the potential for uneven AI reliability across edge cases, multilingual contexts, and highly customized transaction structures. Buyers will need to balance automation enthusiasm with controlled adoption, particularly in regulated industries or multi-entity environments where auditability and explainability remain critical.
PW Consulting
Infrastructure Economics and Compliance as Strategic Variables
The economics of cloud infrastructure and the evolving regulatory landscape will increasingly influence software strategy. As compute and storage demands intensify, providers will need to manage cost structures more deliberately, potentially influencing pricing tiers, feature packaging, and data handling models. Regional compliance, data residency expectations, and sustainability-related review processes will add complexity to deployment planning, especially for global organizations. Vendors that design for flexibility—through regional deployments, modular architecture, and transparent cost models—will be better positioned to maintain scalability without eroding customer trust.
For buyers, this environment calls for more rigorous due diligence on provider infrastructure roadmaps, data governance practices, and long-term service continuity. The risk is not only cost escalation but also potential deployment friction if local permitting, energy constraints, or regulatory reviews slow capacity expansion. Organizations that treat infrastructure resilience and compliance alignment as evaluation criteria today will be better insulated from disruption tomorrow.
Ecosystem Embedding and the Blurring of Financial Toolsets
The third major trend is the progressive integration of accounting software into broader financial and operational ecosystems. Banking integrations, embedded payments, payroll connectivity, and practice management workflows are reducing the isolation of accounting tools and making them part of a continuous enterprise data flow. This convergence benefits users through reduced manual handoffs and improved data consistency, but it also complicates vendor landscapes. Procurement teams will face an expanding set of integration choices, partnership dependencies, and data-sharing considerations. Vendors that offer open, well-documented integration frameworks and clear data portability options will capture advantage in an environment where lock-in risk is increasingly scrutinized.
The opportunity here lies in building or selecting platforms that operate as connective tissue rather than closed silos. Enterprises that align accounting systems with treasury, payments, and operational planning tools can accelerate close cycles, improve forecast accuracy, and support more agile resource allocation. The uncertainty is that rapid ecosystem expansion can outpace governance maturity, creating data quality, access control, and vendor management challenges if not addressed early.
Strategic Implications for Decision Makers
For enterprise and mid-market executives evaluating online accounting software, the immediate priority is to reframe selection criteria around workflow continuity and integration economics rather than feature checklists. Platforms should be assessed on their ability to embed into existing financial operations, reduce reconciliation and reporting friction, and support the analytical needs of finance teams as they shift from data processing to interpretation and advisory work. Migration planning should account not only for transaction history and reporting requirements but also for training, process redesign, and the talent implications of higher automation levels. Organizations that treat adoption as a finance-transformation initiative rather than a software upgrade will derive materially greater value.
Cloud Accounting Software Market
For investors and corporate development teams, the market signals point toward selective value creation rather than uniform sector upside. AI-enabled accuracy, ecosystem integration, and enterprise-grade consolidation capabilities are becoming primary drivers of competitive differentiation. Companies that rely solely on commoditized cloud bookkeeping or that lack credible paths to interoperability and workflow depth face margin and retention pressure. Conversely, providers with strong partner networks, clear segment focus, and credible automation roadmaps are positioned to capture share as buyers move from basic digitization to performance-oriented financial tooling. Due diligence should emphasize retention dynamics, integration breadth, customer segment alignment, and infrastructure cost resilience.
For procurement and finance operations leaders, the practical mandate is to build evaluation frameworks that anticipate the next cycle of platform evolution. This includes demanding transparency on data handling, AI-assisted workflows, update cadence, and integration commitments; testing platforms against real operational scenarios rather than scripted demos; and negotiating contracts that preserve flexibility as requirements evolve. Early attention to data governance, user adoption planning, and cross-functional workflow mapping will reduce the risk of fragmented deployments and underutilized capabilities. In practice, the organizations gaining the most from online accounting software are those that align platform selection with broader finance operating models and treat tooling as an enabler of process redesign rather than a standalone purchase.
The strategic landscape of online accounting software is shifting from incremental digitization to integrated financial operations, shaped by AI maturation, infrastructure and regulatory realities, and increasingly connected enterprise ecosystems. Market sizing and growth trajectories provide a useful directional backdrop, but the durable sources of advantage will come from execution quality, workflow depth, and the ability to reduce friction across the full finance function. Decision makers who evaluate platforms with these dynamics in mind, and who seek detailed segmentation, vendor benchmarking, and region-specific deployment considerations, will be better positioned to convert market growth into operational advantage. For a closer examination of segment-level dynamics, competitive benchmarking, and tailored strategic recommendations, the full PW Consulting market research report offers a more granular view of the opportunities and trade-offs ahead.
For detailed analysis of this topic, please visit the official page: Online Accounting Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Foaming Creamer Market: Strategic Trends and Commercial Opportunities Beyond Steady Growth
Market Snapshot and Structural Challenges
The global foaming creamer market has demonstrated consistent, albeit moderate, expansion over the past half-decade, moving from approximately 150.0 million USD in 2020 to an estimated 189.5 million USD in 2025. This trajectory reflects a compound annual growth rate of 3.5 percent, with projections pointing toward 240.25 million USD by 2032. While the growth pace is not explosive, it signals a mature yet resilient category where incremental innovation and regional penetration matter more than headline expansion. The market’s stability is anchored in its dual role: serving as a functional ingredient for beverage formulation and as a value-enhancing component in foodservice and retail channels.
Beneath the steady valuation curve lies a set of structural inflection points that demand strategic attention. First, raw material dependency remains a persistent volatility driver. Foaming creamer powders require precise formulation parameters, typically relying on 18–24 percent milk solids and 19–23 percent fat content sourced from dairy or palm and coconut oil derivatives. Fluctuations in agricultural commodity pricing, coupled with shifting sustainability expectations around palm oil and dairy sourcing, create margin compression risks for manufacturers that lack diversified supply architectures.
Second, regulatory scrutiny is intensifying across major markets, particularly around labeling transparency, additive disclosures, and nutritional claims. In the United States, food safety authorities continue to monitor foaming creamer products for compliance with health and safety criteria, while the European Union maintains stringent oversight of non-dairy ingredients, emphasizing clean-label alignment and plant-based standard adherence. Compliance is no longer a checkbox exercise; it is a competitive differentiator that shapes consumer trust, retail placement, and cross-border trade feasibility.
Non-dairy Creamer Market
Third, production economics remain tightly linked to specialized infrastructure and labor-intensive quality control. Spray-drying processes, which are essential for achieving stable foam characteristics in both hot and cold applications, require dedicated facilities and rigorous formulation oversight. This creates a barrier to entry but also concentrates operational complexity among established players. Companies that cannot manage the intersection of process precision, ingredient sourcing, and cost efficiency will struggle to scale profitably in an increasingly price-aware environment.
Core Drivers Shaping Market Trajectory
Technological evolution in ingredient engineering continues to redefine what foaming creamers can deliver. The shift from generic texture enhancement to controlled foam architecture—where stability, mouthfeel, and layering are engineered for specific brewing systems and instant beverage formats—has opened new formulation pathways. Granulation and spray-drying advancements enable manufacturers to tailor fat-to-solids ratios with greater precision, allowing products to perform consistently across single-serve brewing equipment, ready-to-mix beverage applications, and foodservice preparation. This technical maturation is gradually decoupling product performance from reliance on traditional dairy-only inputs, expanding the design space for non-dairy and hybrid formulations.
Policy and regulatory dynamics are simultaneously acting as both constraint and catalyst. Stringent ingredient standards in developed markets are pushing formulators toward cleaner profiles, fewer synthetic additives, and more transparent sourcing narratives. Rather than treating compliance as a defensive cost, leading companies are integrating regulatory alignment into product architecture early in the development cycle. This proactive stance reduces time-to-market friction, strengthens retailer confidence, and positions brands favorably in regions where labeling and nutritional claim verification are becoming purchasing prerequisites. The regulatory environment is therefore reshaping the competitive baseline: products that meet clean-label expectations without sacrificing functional performance are gaining shelf and menu precedence.
Demand-side behavior is shifting along two reinforcing axes: premiumization and convenience. Consumers and foodservice operators alike are prioritizing beverage experiences that combine visual appeal, consistent foam structure, and familiar flavor profiles with rapid preparation. Instant drink formats, specialty coffee applications, and milk tea categories have normalized the expectation that a creamer should contribute not just richness but also a stable, enduring foam layer. At the same time, retail and foodservice buyers are seeking formulations that simplify inventory management, reduce preparation variability, and support menu standardization across locations. This convergence favors products designed for predictable performance in both hot and cold systems, with application versatility becoming a key purchasing criterion.
Supply chain and cost structure evolution is introducing both pressure and opportunity. Labor-intensive formulation and quality control steps, combined with the need for specialized spray-drying infrastructure, mean that production efficiency is increasingly tied to process automation, batch consistency, and supplier coordination. Companies that invest in tighter quality loops, ingredient traceability, and flexible production scheduling are better positioned to absorb raw material volatility while maintaining consistent output. Conversely, fragmented sourcing strategies and underinvestment in process control can quickly erode margin stability when commodity inputs or logistics costs shift. The net effect is a market where operational discipline is becoming a strategic asset as much as formulation expertise.
Competitive Landscape and Positioning Dynamics
The competitive field is characterized by a mix of specialized regional players and broader ingredient groups, with the top three firms collectively accounting for roughly 45 percent of market revenue and the top five reaching approximately 65 percent. This concentration reflects a market where scale, process capability, and application-specific formulation knowledge confer meaningful advantages, yet it also leaves room for targeted entrants that solve specific performance or compliance gaps.
Chia-Tza-Teng International Co., Ltd. has built its positioning around foaming creamer powders engineered for instant thick foam in coffee and milk tea sachets, leveraging granulation technology to deliver 18–24 percent milk solids and 19–23 percent fat content. Its recent catalog expansion in early 2026 signals continued investment in product visibility and application breadth, reinforcing a strategy centered on formulation consistency and format-specific performance. Royal FrieslandCampina N.V. has differentiated through its Kievit® Vana-Cappa line, which focuses on creating a stable foam layer with lasting texture for instant drinks and single-serve brewing systems. This positioning aligns closely with the convenience and standardization demands of modern foodservice and retail beverage formats, emphasizing reliability across preparation methods. Kerry Group plc, through its Almer division, supplies spray-dried foaming creamer powders for hot and cold beverages, with sourcing flexibility spanning palm or coconut oil bases. Its strategy highlights application adaptability and infrastructure alignment, recognizing that stable foam performance depends as much on drying and formulation control as on ingredient selection. PT Lautan Natural Krimerindo operates with a focused non-dairy orientation, manufacturing foaming creamer specifically designed to deliver coffee froth on top of beverages. Its participation in major trade platforms, including Food Taipei Mega Shows in mid-2026, underscores a regional growth play that targets emerging beverage categories and export-oriented distribution channels.
The landscape is evolving along a dual path of consolidation and segmentation. Larger ingredient groups are leveraging integrated supply chains, regulatory expertise, and cross-application portfolios to defend share and capture adjacent opportunities. At the same time, specialized manufacturers are carving out niches by emphasizing format-specific foam performance, regional taste preferences, and cost-competitive non-dairy alternatives. New entrants tend to succeed not by competing on broad commodity positioning, but by solving a precise formulation, compliance, or distribution challenge that incumbents are not optimized to address. This dynamic suggests that the next phase of competition will be less about overall market size and more about application ownership, ingredient transparency, and supply chain agility.
Worldwide Shaving Foam Market
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interconnected trends. First, clean-label and plant-forward formulation will move from differentiation to baseline expectation. As regulatory frameworks tighten and consumer preferences continue to favor transparent ingredient lists, foaming creamers that deliver stable performance with simplified profiles will capture disproportionate attention in retail and foodservice procurement. The commercial opportunity lies in developing formulations that maintain foam integrity and mouthfeel while reducing additive complexity and aligning with regional plant-based standards. Companies that invest early in this transition will be better positioned to secure shelf placement, streamline compliance, and respond to buyer requirements without last-minute reformulation.
PW Consulting
Second, application-specific engineering will become a more decisive competitive lever. Foam stability, temperature tolerance, and texture consistency are increasingly evaluated against specific use cases, from single-serve brewing systems to instant beverage mixes and foodservice milk tea preparation. The opportunity here is to design product architectures that are validated across multiple preparation environments, reducing formulation risk for buyers and enabling broader deployment. Manufacturers that can document performance across hot and cold systems, provide clear usage guidance, and support menu standardization will find stronger purchase justification and higher switching costs for their customers.
Third, supply chain resilience and input diversification will separate scalable operators from marginal players. Given the reliance on dairy solids, palm or coconut oil derivatives, and specialized drying infrastructure, companies that build flexible sourcing strategies, monitor commodity exposure, and invest in process consistency will be more capable of protecting margins during volatility. The associated opportunity is to pair ingredient flexibility with formulation stability, ensuring that changes in raw material inputs do not compromise foam performance or regulatory alignment. Risks remain, particularly where procurement strategies are overly concentrated, where reformulation capacity is limited, or where regional compliance requirements shift faster than product development cycles can accommodate.
Actionable Directions for Decision-Makers
For manufacturers, the priority should be to align formulation strategy with both performance validation and regulatory foresight. Investing in application testing across hot and cold beverage systems, documenting foam stability and texture consistency, and building ingredient architectures that can accommodate sourcing variation without sacrificing clean-label compliance will create durable advantages. Companies should also evaluate where spray-drying capacity, quality control rigor, and batch consistency can be strengthened to reduce operational risk and improve margin predictability.
For investors, the strategic question is less about overall market growth and more about which capabilities will command pricing power and share resilience. Interest should center on players that demonstrate differentiated application engineering, flexible ingredient sourcing, and a credible path to clean-label compliance across key regions. Monitoring how incumbents and niche players respond to regulatory evolution, raw material volatility, and foodservice standardization trends will provide early signals about which business models are most likely to scale profitably.
For procurement and sourcing leaders, the focus should be on reducing formulation and supply risk while securing consistent beverage performance. This means prioritizing suppliers that can provide transparent ingredient profiles, validated foam stability across intended applications, and clear guidance on usage compatibility with existing brewing or mixing systems. Building redundancy into sourcing, evaluating total cost beyond unit price, and requiring documentation that supports labeling and nutritional claim compliance will help protect product quality and reduce downstream disruption.
Closing Perspective
The foaming creamer market is entering a phase where steady valuation growth masks increasingly important shifts in formulation expectations, regulatory alignment, and supply chain discipline. Companies that treat these shifts as strategic design constraints rather than operational nuisances will be better positioned to capture application-specific demand, defend margins, and expand into higher-value beverage categories. For decision-makers seeking deeper segmentation data, regional demand patterns, and tailored recommendations aligned with specific product portfolios or investment criteria, a detailed market report can provide the granular context needed to convert these directional insights into execution plans.
For detailed analysis of this topic, please visit the official page: Foaming Creamer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Snow Chain Market 2026: Beyond 5.35% CAGR, Unpacking $298M Growth Drivers
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Snow Chain Market: A 2025 Executive Briefing
The snow chain market is navigating a period of measured expansion, shaped by evolving winter preparedness requirements, shifting product preferences, and tightening performance expectations across regions. From 2020 through 2025, the industry built a steady growth trajectory, with 2025 standing as the latest confirmed baseline. Looking ahead through the forecast horizon to 2032, market momentum is projected to continue at a compound annual growth rate of 5.35%, translating into a measured but consistent uplift in total value over the period. Rather than signaling a sudden surge, this pace reflects a maturing market where incremental innovation, regulatory alignment, and demand-side habit changes are working in tandem. For decision-makers, the implication is clear: snow chains are no longer treated as a seasonal commodity alone, but as a regulated, performance-critical component of winter mobility ecosystems.
The broader market structure reflects a balanced mix of traditional and alternative traction solutions. Metal-based systems continue to command the largest share of attention, particularly where durability, load capacity, and repeated mechanical use are prioritized. Nonmetal alternatives, including textile traction devices, have carved out a meaningful position by emphasizing ease of handling, lower vehicle impact, and quick deployment. This dual-track product landscape matters because it mirrors a broader industry shift: buyers are increasingly weighing convenience and compliance alongside raw strength. At the same time, concentration remains comparatively moderate, with the top three players accounting for roughly a quarter of the market and the top five approaching just over a quarter. That fragmentation does not indicate weakness; instead, it points to a space where regional specialization, application expertise, and product positioning still create room for distinct competitive advantages.
Market Context and Core Structural Challenges
Despite the favorable growth outlook, the snow chain industry is not moving through calm waters. Executives evaluating participation, investment, or procurement strategies should pay close attention to a set of structural tensions that are reshaping how products are designed, sold, and deployed.
Polarized Demand Between Durability and Convenience
One of the persistent challenges in this market is the tension between long-established metal chain expectations and the growing appeal of lightweight, user-friendly traction alternatives. Metal chains remain the default in environments where repeated use, heavy loads, and harsh surface conditions are common. Their strength and familiarity make them the safe choice in many fleet, construction, and mountainous logistics settings. At the same time, textile and composite products are gaining credibility among passenger vehicle owners and lighter commercial users who value faster installation, reduced wear on road surfaces, and simpler storage. The challenge for manufacturers and distributors is not simply offering both categories, but aligning each with the right use case, performance claim, and pricing logic without blurring distinctions that matter to regulators and end users.
Regulation as Both Catalyst and Complexity
Winter traction requirements are undergoing visible updates in multiple jurisdictions, increasing the strategic importance of compliance-ready product portfolios. In several markets, authorities have refined expectations around when traction devices must be carried or fitted, and in some cases they have clarified preferred device types for specific conditions or vehicle classes. This is beneficial for the market as a whole because it strengthens the practical case for carrying chains or approved alternatives. Yet it also introduces complexity. Regulations can favor particular technologies in particular contexts, encourage faster product cycles, and raise the bar on documentation, testing, and quality assurance. Companies that treat compliance as an afterthought risk losing credibility with fleet buyers, dealer networks, and public-sector procurement teams.
Quality, Standards, and the Cost of Trust
A third challenge lies in the increasing expectation that traction products meet consistent international quality, safety, and environmental standards. Certified manufacturers are expected to demonstrate not only fit and function, but also controlled production practices and reliable performance under variable winter conditions. This raises the barrier for informal or loosely managed entrants and rewards players that have invested in disciplined manufacturing and testing. For the broader market, the upside is stronger buyer confidence and less price-only competition. The downside is that margins can be pressured when companies must absorb higher compliance, testing, and documentation costs while still competing in a fragmented landscape.
Key Drivers Reshaping the Snow Chain Market
The market’s trajectory is being pushed forward by several reinforcing forces. None of these drivers operates in isolation; together, they are redefining which products win, where growth concentrates, and how quickly new solutions can scale.
Technology and Product Design Innovation
Product innovation remains one of the most visible levers in the market. Easy-fit mechanisms, improved tensioning systems, more predictable fitment across tire sizes, and clearer integration with vehicle specifications are all helping reduce the friction historically associated with traction devices. In parallel, textile-based traction products have matured as practical alternatives in defined use cases, giving buyers a lighter, less intrusive option that can satisfy many everyday winter-driving needs. The strategic significance of this innovation is not limited to convenience. Better design lowers the barrier to proper use, which matters because a traction device only delivers value if it is deployed correctly and consistently. Companies that reduce installation time, improve fit confidence, and make storage and transport easier are indirectly strengthening compliance and safety outcomes.
A Regulatory Environment That Is Becoming More Explicit
Recent winter-equipment updates provide a clear example of how policy can shape demand. In France, mandatory winter equipment requirements for designated mountainous areas have been refreshed for the November 2025 to March 31, 2026 period, with metal snow chains or textile snow socks specified as acceptable options for light vehicles and vans. The same guidance also notes that metal chains are recommended over textile socks for frequent use in mountainous settings during that window. This distinction is strategically important because it signals that authorities are not treating all traction devices as interchangeable in every context. Meanwhile, in Colorado, a revised Passenger Vehicle Traction Law effective from fall 2025 requires chains or approved alternative devices for some 4WD/AWD vehicles without qualifying winter tires during severe storms. These changes reinforce a broader point: traction requirements are becoming more specific, more conditional, and more tied to real-time severity rather than generic seasonal memory. For manufacturers, that means product messaging must be precise, and portfolios must be flexible enough to address both baseline mandates and storm-triggered enforcement.
Changing User Behavior and Vehicle Mix
Demand-side behavior is shifting in ways that favor both safety and versatility. Across passenger and light commercial segments, users increasingly expect traction solutions that can be deployed without specialized effort, stored compactly, and trusted to work across a range of conditions. At the same time, vehicle fleets are not uniform; the proportion of all-wheel and four-wheel drive vehicles, varying tire sizes, and mixed light-commercial use patterns complicates one-size-fits-all product logic. Buyers are therefore looking for solutions that reduce uncertainty: clear fit guidance, application-specific recommendations, and devices that can be justified as a practical part of winter readiness rather than an emergency-only purchase. The business implication is that product leadership increasingly depends on the surrounding experience—guidance tools, compatibility clarity, and confidence in real-world performance—as much as on the chain itself.
Tire Protection Chains Market
Supply Chain Discipline and Cost Structure Pressures
Cost dynamics are also shaping strategy. Materials, production consistency, logistics, certification, and inventory planning all influence the final economics of traction products. Because snow chains are highly seasonal in many markets, inventory misalignment can create noticeable margin volatility. In addition, standards-aligned manufacturing and testing add structural cost but also create differentiation. Companies that can balance disciplined cost control with dependable quality are better positioned to serve both price-sensitive volume channels and performance-sensitive buyers. The supply chain challenge, then, is not simply to cut cost, but to manage a more complex value equation in which reliability, certification, and availability are all part of the price proposition.
Competitive Landscape and Leadership Strategies
The competitive field in this market is shaped by players with distinct regional strengths, product orientations, and customer interfaces. Rather than a single dominant template, the landscape shows several viable paths to relevance, each tied to a different interpretation of what buyers value most.
Differentiated Positioning Among Established Players
Several companies illustrate how strategic positioning can diverge even within the same category. Pewag Group has built a manufacturing footprint spanning Austria, the Czech Republic, and Pueblo, Colorado, supporting production for cars, SUVs, light trucks, heavy trucks, and utility vehicles. That broad vehicle coverage and multi-site production structure suggests an emphasis on scale, application breadth, and supply resilience across heavier-duty and utility segments. König, by contrast, has carved an identity around consumer-facing snow chains with patented easy-fit technologies and vehicle integration solutions. Its approach highlights the importance of usability and product design in the passenger and light-vehicle segments, where fit confidence and installation simplicity can be decisive purchase factors. RUD Group contributes a wider traction-device narrative, spanning snow chains, automatic traction chains, and off-road traction devices for passenger, truck, and industrial vehicles. That positioning gives the company a bridge between classic winter traction and more specialized mobility demands, which can be valuable in mixed-use and industrial contexts.
PW Consulting
Thule Group adds another angle by developing snow chains and traction devices with an emphasis on integration with vehicles and accessories, reflecting a broader mobility-and-safety ecosystem mindset. Peerless Chain Company reinforces the North American market with light truck, SUV, and passenger snow chains, including Auto-Trac automatic models and tire finder tools. The inclusion of fitment tools is notable because it lowers the friction of choosing the right device, an important commercial advantage in channels where compatibility questions often slow purchase decisions. Quality Chain Corp stands out as a major North American wholesaler and supplier for passenger cars, light trucks, and SUVs, underscoring the continued importance of distribution strength and channel reach in a market where availability during the winter window can be as important as product design. AutoSock Operations AS represents the textile traction segment, offering lightweight snow socks as an alternative traction device that meets recognized safety expectations. Its presence in the competitive landscape signals that alternative-material traction is now an established commercial category, not a niche curiosity.
How the Landscape Is Evolving
Several evolution patterns are worth watching. First, the market appears to be strengthening around players that can combine regional presence with product clarity. Companies that serve both consumers and professional buyers often need separate value propositions, because the criteria for purchase differ: everyday users prioritize ease and confidence, while fleets and commercial operators prioritize durability, compliance, and operational consistency. Second, the competitive field is likely to see continued specialization rather than only broad consolidation. The presence of strong wholesalers, integrated mobility brands, automatic-traction specialists, and textile-alternative producers indicates that customers are choosing among different solution philosophies. Third, new entrants or expanding players may gain ground by reducing friction in fitment, improving transparency around compatibility, or offering stronger warranty and support structures that make winter-readiness purchasing less risky. In a moderately concentrated market, differentiation can be achieved through experience, distribution, and application focus as much as through raw product novelty.
Forward-Looking Trends and Commercial Opportunities
Looking toward the next three to five years, the snow chain market is likely to be shaped by a small number of high-impact trends. Each carries both opportunity and risk, and the strategic value lies in identifying where a company’s capabilities can align with the direction of demand.
Traction Products as Part of a Compliance-Driven Readiness Model
Winter traction is increasingly treated as part of a broader readiness discipline rather than an optional accessory. As winter equipment expectations become more defined and more conditional, buyers in both consumer and commercial channels are likely to seek products that fit cleanly into compliance planning, fleet policies, and seasonal preparation routines. The commercial opportunity here is to build portfolios and support systems that make readiness easier to implement at scale. That can include clearer application guidance, stronger fitment tools, and product lines that map well to common regulatory scenarios. The risk is that generic or poorly positioned offerings may be squeezed out when buyers compare devices against explicit legal or policy requirements rather than convenience alone.
Continued Expansion of Alternative Traction Solutions in Defined Use Cases
Textile and other nonmetal traction alternatives are likely to continue gaining relevance in specific segments where ease of use, lower vehicle impact, and quick deployment are particularly valuable. The opportunity lies in matching these products to the right conditions and communicating their strengths without overstating their applicability. In mountainous or frequent-use contexts, the preference for metal chains in some guidance underscores the need for balanced portfolio strategy. Companies that can clearly differentiate where each technology fits—and why—will be better positioned to defend margin and customer trust. The risk is mis-positioning: if alternative traction products are sold into use cases where durability or abrasion resistance is the priority, satisfaction and reputation can erode quickly.
Standardization, Quality Assurance, and the Premium on Reliability
As expectations around quality, safety, and certification become more embedded across regions, reliability is likely to command a stronger premium. This favors manufacturers and distributors that can demonstrate consistent production, controlled quality systems, and credible performance claims. The commercial opportunity is to use quality assurance not only as a compliance expense, but as a market-facing differentiator that supports pricing, buyer confidence, and institutional sales. The uncertainty is that standards and enforcement expectations can continue to evolve, and companies that do not keep pace may face both commercial and reputational exposure.
Strategic Actions for Decision-Makers
For executives operating in or adjacent to this market, the most valuable next step is to convert high-level trends into concrete decisions about product mix, channel strategy, and compliance readiness.
Winter Tire Market
For Manufacturers and Product-Led Players
Build product architectures that separately address durability-critical, ease-of-use, and compliance-driven scenarios. A strong portfolio should make it obvious which device is intended for repeated mountain use, which is optimized for quick deployment, and which is best suited to a particular vehicle class or regulatory context. It is equally important to invest in fitment clarity and compatibility tools, because reducing selection friction can improve both conversion and proper use. Manufacturers should also treat certification and quality discipline as market-facing assets, not back-office requirements, especially when institutional buyers and larger fleets evaluate suppliers.
For Investors and Strategic Acquirers
Evaluate opportunities through the lens of channel strength, application coverage, and regional regulatory alignment rather than product category alone. A distributor with strong winter-window availability in key markets, a manufacturer with broad vehicle coverage, or a brand with a strong usability and integration story can each create defensible positions. Due diligence should pay close attention to seasonality risk, inventory planning, certification readiness, and the ability to serve both consumer and professional buyers without blurring the value proposition. Businesses that combine product credibility with dependable supply and clear positioning are likely to be more resilient than those competing primarily on price.
For Fleet Operators, Dealers, and Procurement Teams
Treat traction procurement as a readiness investment with compliance and safety implications, not merely a seasonal purchase. Selection should be informed by vehicle mix, likely operating conditions, and the specific requirements that apply in the regions where vehicles operate. Where conditions include frequent mountainous use or strict enforcement windows, it is prudent to match device type to the intended use pattern and to ensure that driver training, storage, and inspection practices support correct deployment. Procurement strategies that incorporate fitment tools, clear compatibility checks, and dependable seasonal availability can reduce operational risk more effectively than purchasing decisions based on lowest unit cost alone.
Closing Perspective
The snow chain market is entering a phase in which growth is steady, but the definition of winning is becoming more nuanced. Regulatory clarity, product innovation, application-specific demand, and quality expectations are all pushing the market toward more disciplined competition. The companies and buyers that benefit most will be those that treat traction devices as part of a broader winter-mobility strategy: the right device for the right condition, supported by clear guidance, reliable supply, and credible quality. For organizations seeking more granular segmentation, regional dynamics, and tailored strategic options, a closer look at the full research scope can help translate these market signals into precise action plans.
For detailed analysis of this topic, please visit the official page: Snow Chain Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Air Sampling Pumps Market: Why 4.53% CAGR and Asia Pacific Demand Redefine Growth Through 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Air Sampling Pumps Market
Market Trajectory and Structural Pressures
The global air sampling pumps market has established a consistent growth trajectory, with revenue reaching approximately USD 59.34 million in 2025 and projected to climb to USD 80.4 million by 2032. This expansion reflects a compound annual growth rate of 4.53 percent across the 2026 to 2032 forecast period, signaling steady demand evolution rather than speculative boom cycles. Historical performance from 2020 through 2025 shows incremental gains, with year-over-year increases ranging from modest to moderate, reinforcing a market driven by regulatory compliance, occupational health priorities, and environmental monitoring requirements rather than volatile consumer behavior.
Within this landscape, regional concentration patterns reveal distinct maturity levels. Asia Pacific currently commands the largest revenue share, followed by North America and Europe, while Latin America and the Mideast and Africa represent smaller but developing footprints. The geographic distribution aligns closely with industrial activity density, regulatory enforcement intensity, and the spread of occupational hygiene programs. Product segmentation remains balanced between personal air sampling pumps and area air sampling pumps, each serving distinct monitoring requirements. Application-wise, industrial manufacturing, health industry, and environment industry collectively anchor demand, though their relative weight shifts as regional compliance priorities mature.
Key Challenges and Inflection Points
Despite the predictable growth path, the market faces structural challenges that will test vendor positioning and buyer decision-making in the coming years. The first challenge centers on regulatory alignment across jurisdictions. Monitoring standards increasingly demand tighter control over flow stability, pulsation limits, and post-calibration verification. Equipment that previously met baseline requirements may now fall short when deployed in regions adopting upgraded directives or stricter interpretation of existing standards. Manufacturers must balance compliance readiness with cost accessibility, particularly when serving multi-regional clients with divergent enforcement timelines.
The second challenge involves the tension between precision and portability. Occupational and environmental monitoring teams increasingly require devices that maintain laboratory-grade accuracy while fitting into confined workspaces, mobile monitoring setups, or rapid-deployment scenarios. Engineering teams must navigate competing design priorities: smaller form factors, extended battery performance, and reduced weight must not compromise calibration consistency or flow reliability. Buyers evaluating procurement options often face trade-offs between ruggedized configurations for heavy industrial settings and compact units optimized for indoor air quality or healthcare environments.
A third inflection point relates to market concentration and buyer leverage. The market remains moderately consolidated among established manufacturers, which creates both stability and pricing pressure. While leading vendors benefit from brand recognition, service networks, and long-standing compliance credentials, buyers are increasingly equipped with more information and alternative sourcing options. This dynamic pressures incumbents to justify premium positioning through demonstrable performance advantages, service quality, and integrated support ecosystems rather than heritage alone.
Core Growth Drivers Reshaping Demand
Technology Innovation and Performance Evolution
Product development is shifting from basic flow delivery toward smarter monitoring capability. Recent catalog updates and product introductions signal a clear direction: manufacturers are refining pump platforms to address flow stability, pulsation control, calibration ease, and connectivity for workflow integration. For example, updated personal sampling pump catalogs have introduced refined model specifications that emphasize usability, calibration verification, and application-specific configurations. Meanwhile, new portable air sampling pump additions reflect demand for lighter, more adaptable equipment in indoor air quality and environmental monitoring contexts.
This innovation trajectory matters because it connects directly to operator efficiency and data confidence. Devices that simplify calibration, reduce setup time, and maintain stable flow characteristics under variable conditions reduce the risk of non-compliant sampling results. In practical terms, engineering improvements are not merely product features; they are risk mitigation tools for industrial hygienists, safety managers, and environmental consultants who must produce defensible monitoring records.
Active Air Sampler Market
Regulatory and Standards Pressure as Compliance Catalyst
Regulatory frameworks continue to act as one of the strongest demand drivers. Occupational exposure monitoring depends on methods that require calibrated air sampling pumps with stable flow performance, and several standards reinforce this expectation. ISO 13137:2019, for instance, requires personal sampling pumps to maintain pulsation not exceeding 10 percent of the flow rate to support accurate workplace exposure monitoring. NIOSH NMAM methods reinforce the need for constant flow in analyses involving asbestos, lead, and crystalline silica. OSHA sampling methods further specify flow ranges and post-calibration verification expectations for personal air sampling pumps.
At the regional level, the EU Worker Exposure Directive revision has strengthened pulsation and flow stability requirements across member states, raising the compliance bar for organizations operating in Europe or supplying equipment into that market. These regulatory dynamics create a structural pull for equipment that can demonstrably meet evolving requirements. They also raise the stakes for buyers who must ensure that monitoring programs remain defensible during audits, incident investigations, or internal compliance reviews.
Demand-Side Shifts in Occupational Health and Environmental Monitoring
Demand is increasingly shaped by a broader interpretation of exposure risk. Industrial operations continue to represent a major application base, but health industry and environment industry usage is expanding as organizations broaden monitoring beyond traditional manufacturing floors. Healthcare settings, public facilities, and indoor air quality programs are driving interest in portable and area monitoring equipment that can support indoor environments, infection control-related airflow assessments, and general environmental surveillance.
Simultaneously, workplace safety culture is becoming more data-oriented. Safety teams are placing higher value on repeatable measurements, documented calibration, and equipment that integrates smoothly into field workflows. This shift favors vendors that can support not only the hardware but also the operational discipline surrounding sampling programs. In effect, the market is rewarding solutions that make compliance easier to execute consistently rather than only occasionally.
Supply Chain Realities and Cost Structure Considerations
Cost structures remain an important factor in procurement decisions, especially as organizations balance compliance budgets against broader operational spending. While the market is not experiencing volatile commodity shocks as a dominant narrative, equipment durability, service availability, and replacement part accessibility still influence total cost of ownership. Procurement teams increasingly evaluate pumps not as isolated instruments but as part of a monitoring system that includes calibration equipment, maintenance support, and training.
This broader purchasing lens benefits manufacturers with strong service networks and transparent support models. It also elevates the importance of product longevity and maintainability. In segments where buyers deploy equipment across multiple sites or rotating crews, reliability and service responsiveness can outweigh marginal price differences. As a result, suppliers that can deliver consistent field performance and predictable upkeep gain an advantage in multi-year purchasing decisions.
Competitive Landscape and Strategic Positioning
Established Players and Differentiating Strengths
The market features a set of well-known manufacturers with distinct product and service orientations. SKC Inc. has built recognition around personal air sampling pumps used in occupational exposure monitoring, with pump families designed for field sampling workflows. Sensidyne LP is associated with Gilian personal and high-flow air sampling pumps, along with calibrators supporting industrial hygiene and area sampling, which positions the company at the intersection of sampling and calibration equipment. Zefon International, Inc. offers personal and area environmental monitoring pumps, expanding its relevance across both occupational and environmental use cases. Casella USA provides personal air sampling pumps with connectivity features aimed at workplace exposure assessments, reflecting a strong emphasis on usability and field integration.
These companies differentiate not only through product specifications but also through how they support compliance workflows. Some compete on pump performance and pulsation control. Others emphasize calibration tools, training, documentation support, and field-ready design. The practical distinction for buyers often lies in whether the vendor can reduce the operational burden of sampling programs through integrated hardware, calibration consistency, and reliable after-sales support.
Recent Developments as Indicators of Strategic Focus
Recent company activities provide insight into how incumbents are navigating the market. Trade show participation by major pump and calibrator suppliers has continued through 2025, with exhibition activity at industry events highlighting ongoing engagement with occupational hygiene communities. These appearances are not mere marketing exercises; they function as channels for demonstrating flow performance, calibration practices, and equipment reliability to audiences that evaluate compliance-critical tools.
Product catalog updates have also underscored incremental innovation. Updated pump catalogs have introduced refined model details, while newer portable pump additions have broadened portfolios for indoor and environmental monitoring applications. Such moves suggest that established manufacturers are pursuing portfolio expansion and specification refinement rather than disruptive product replacement. This measured approach aligns with a market where compliance acceptance, service history, and user familiarity carry significant weight.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The competitive structure appears likely to evolve through a combination of consolidation and targeted differentiation. Moderate market concentration gives leading firms room to defend positions through service networks and compliance credentials, but it also leaves space for specialized entrants in subsegments such as compact indoor air quality monitoring, improved connectivity for field data workflows, or region-specific compliance configurations. Potential consolidation may occur where service coverage, calibration support, and geographic reach become decisive purchase factors.
At the same time, fragmentation remains possible in application-specific niches. Buyers in healthcare environments, environmental consulting, or specialized industrial processes may prioritize features that larger generalist portfolios do not fully optimize. This creates opportunity for companies that can deliver focused solutions, provided they can also meet the compliance and reliability expectations associated with sampling instrumentation.
Forward-Looking Trends and Commercial Implications
Trend 1: Compliance-Driven Product Specifications Will Become a Baseline Expectation
Over the next three to five years, flow stability, pulsation control, and calibration verification are likely to transition from desirable features to baseline requirements in many procurement processes. As regional directives and occupational hygiene methods continue to reinforce consistent sampling performance, equipment that cannot document stable performance will face increasing friction in regulated environments. The commercial implication is clear: manufacturers that proactively align product design and documentation with evolving standards will reduce adoption barriers for compliance-focused buyers.
For procurement teams, this trend increases the importance of verification. Purchasing decisions will need to account not only for flow range and portability but also for how easily a pump can be calibrated, verified, and documented in routine use. Equipment that simplifies compliance workflows will likely command stronger preference in competitive bids.
Trend 2: Connectivity and Field Workflow Integration Will Gain Commercial Weight
As monitoring programs become more data-driven, devices with Bluetooth connectivity, streamlined field setup, and better integration into exposure assessment workflows will become more relevant. Connectivity does not replace measurement accuracy, but it can reduce administrative burden, improve record-keeping consistency, and support faster field decisions. In practical terms, the market is moving toward tools that help teams manage sampling programs more efficiently, not just collect samples more accurately.
Microbial Air Samplers Market
This trend opens commercial opportunities for vendors that can link hardware performance with workflow convenience. It also creates a differentiation path for companies that can demonstrate tangible improvements in setup time, calibration tracking, and exposure assessment documentation. The risk for buyers is overvaluing connectivity without confirming that core sampling performance still meets required standards.
PW Consulting Automotive & Machinery Research Center
Trend 3: Application Diversification Will Redefine Competitive Priorities
Industrial manufacturing will remain a core demand base, but growth in health industry and environment industry applications will encourage product strategies that address a wider range of monitoring contexts. Portable equipment for indoor environments, area sampling for environmental programs, and adaptable configurations for varying flow requirements will become more commercially important. Companies that can serve multiple application profiles without sacrificing compliance credibility will gain broader market relevance.
The corresponding risk is portfolio over-extension. Manufacturers expanding into new application areas must ensure that product claims, calibration support, and service models remain credible for each use case. Buyers in specialized settings will quickly distinguish between equipment that is genuinely suited to their environment and equipment that is merely marketed into it.
Strategic Recommendations for Decision-Makers
For Manufacturers and Suppliers
Prioritize compliance documentation and performance verifiability as core product assets. In a market where regulatory expectations continue to tighten, spec sheets alone are insufficient. Suppliers should ensure that product platforms clearly support flow stability, pulsation control, and calibration verification, and that this support is easy for customers to demonstrate in audits and field use. Equally important is service and calibration support; in compliance-driven purchasing, reliable after-sales infrastructure can be as influential as the instrument itself. Companies should also evaluate whether portfolio expansion into indoor air quality, environmental monitoring, or connectivity-enabled workflows creates genuine differentiation or merely broadens exposure without sufficient support depth.
For Investors
Assess exposure to regulatory-driven demand rather than relying solely on end-market growth narratives. Companies with strong positions in occupational hygiene, industrial hygiene, and compliance-related monitoring are better positioned to benefit from sustained standards pressure. Investment due diligence should examine calibration support, service networks, product acceptance in regulated environments, and the ability to maintain performance claims across multiple jurisdictions. Growth potential is likely to be strongest where vendors can combine product reliability with workflow-relevant features and credible documentation. At the same time, investors should monitor whether expansion into lower-margin application areas dilutes margin stability or operational focus.
For Procurement and Operations Leaders
Evaluate sampling pumps as part of a compliance system rather than as standalone hardware purchases. Total value should account for calibration consistency, field usability, service availability, and the ease of maintaining documentation across multiple sites or rotating crews. Where monitoring programs span different environments, consider whether standardized equipment reduces training burden and audit risk, or whether application-specific tools offer better performance despite increased procurement complexity. It is also prudent to confirm that any connectivity or workflow features do not distract from the fundamental requirement of stable, verifiable flow performance.
Closing Perspective
The air sampling pumps market is moving through a phase where regulatory expectations, workflow efficiency, and application diversification are reshaping purchasing logic. Growth is steady and structurally supported, but competitive advantage will increasingly depend on how well manufacturers translate performance and compliance readiness into practical field value. For buyers, the most effective decisions will come from evaluating equipment against both measurement integrity and operational burden. For suppliers and investors, the opportunity lies in aligning product strategy with the compliance-intensive, workflow-sensitive nature of modern exposure monitoring. Detailed segment-level data, regional breakdowns, and customized scenario analysis can further sharpen these decisions for organizations seeking a more precise path through the market's next phase of development.
For detailed analysis of this topic, please visit the official page: Air Sampling Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Enclosure Market: Why 7.5% CAGR and Strategic Shifts Reshape the Industry by 2032
By pmarketresearch, 2026-09-21
Navigating the Electric Enclosure Market: Strategic Trends and Commercial Opportunities
Market Overview and Pressing Challenges
The electric enclosure market has entered a phase of sustained expansion, with revenue projected to grow from approximately $5.5 billion in 2020 to just over $12.2 billion by 2032. This translates to a compound annual growth rate of 7.5 percent over the forecast period, signaling a market that is outpacing broader industrial equipment segments. The trajectory reflects more than cyclical demand; it is being reshaped by fundamental shifts in how electrical infrastructure is designed, deployed, and protected across multiple end-use ecosystems. Growth has been consistent across recent years, with revenue climbing through 2025 and accelerating into the mid-2030s as new infrastructure build-outs and modernization programs scale globally.
Despite the positive outlook, the industry faces structural friction that will separate agile participants from those relying on legacy operating models. First, the widening gap between standardized protection requirements and increasingly demanding environmental conditions is forcing rapid product adaptation. Enclosures must now accommodate submersion-level ingress protection, extreme thermal cycling, and corrosive exposure while maintaining accessibility for maintenance and compliance verification. Second, regulatory complexity is intensifying across jurisdictions. Compliance frameworks around environmental sealing, installation marking, and voltage-specific safety considerations are becoming more prescriptive, raising the cost of non-compliance and narrowing the window for generic solutions. Third, supply chain volatility and input cost fluctuations continue to pressure margins, particularly for manufacturers balancing metallic and non-metallic material portfolios against fluctuating steel, polymer, and casting costs. These dynamics are not isolated headwinds; they are reshaping competitive criteria and forcing a reevaluation of where value is created in the enclosure value chain.
PW Consulting Automotive & Machinery Research Center
Key Drivers Reshaping Market Trajectory
Technological Innovation and Performance Thresholds
Performance expectations for electric enclosures have evolved beyond basic containment. The integration of advanced sealing architectures, corrosion-resistant material formulations, and pre-engineered mounting interfaces is enabling faster deployment in environments that previously required custom engineering. Die-cast and rigid enclosure platforms are increasingly being offered with expanded ingress protection ratings and surface-mount options, reducing on-site fabrication time and improving consistency across installations. Simultaneously, climate control integration and thermal management features are becoming standard considerations for enclosures deployed in energy distribution, industrial automation, and data center-adjacent applications. This shift is moving enclosures from passive housings toward integrated protection systems, where reliability, serviceability, and environmental resilience directly influence procurement decisions.
Electronic Plastic Enclosure Market
Policy, Standards, and Compliance-Driven Demand
Regulatory and standards-based requirements are becoming a decisive filter in procurement. Enclosures used in electrical installations must align with recognized environmental protection classifications, installation marking directives, and safety considerations for systems operating up to higher voltage thresholds. In parallel, underground utility enclosures and power distribution assets are subject to specifications that address longevity, accessibility, and environmental safety. These requirements are not static; they are tightening in sectors where failure costs are high, such as EV infrastructure and data center power ecosystems. As a result, compliance capability is increasingly a market entry condition rather than a differentiator, pushing manufacturers to standardize certification pathways and design products that can satisfy multiple jurisdictional expectations without costly customization.
Demand-Side Shifts Across Industrial, Energy, and Utility Applications
Demand is being pulled from multiple directions. Industrial control systems continue to represent a substantial share of consumption, but growth is increasingly linked to modernization programs that replace aging enclosures with more durable, modular, and service-friendly alternatives. Energy and power applications are expanding as grid hardening, distributed generation, and EV charging infrastructure accelerate deployment cycles. At the same time, non-metallic conduit and enclosure accessories are gaining traction in applications where weight, corrosion resistance, and installation flexibility matter more than traditional metallic form factors. This diversification is broadening the addressable market while also fragmenting buying criteria, since project owners now weigh environmental exposure, maintenance access, longevity, and installation speed alongside base pricing.
Supply Chain and Cost Structure Evolution
Material availability and pricing dynamics remain central to margin management. Manufacturers with diversified material strategies—spanning steel, stainless steel, fiberglass, and polymer solutions—are better positioned to adapt to regional cost shifts and lead-time disruptions. Procurement teams are also placing greater emphasis on component standardization and interchangeability to reduce inventory complexity and streamline replacement cycles. The competitive advantage is increasingly tied to design efficiency, manufacturing scalability, and the ability to maintain certified product lines without sacrificing responsiveness. Companies that can align material selection with application-specific performance requirements while preserving cost predictability are capturing outsized share in a market where price competition alone is insufficient.
Competitive Landscape and Leading Strategies
Established Players and Strategic Positioning
The market remains moderately concentrated, with the largest players holding meaningful but not dominant shares, leaving room for specialized and regional competitors to thrive through application focus and service capabilities. Leading manufacturers are differentiating through a combination of material breadth, certification maturity, and application-specific engineering rather than volume pricing alone. For example, some firms emphasize rugged die-cast platforms with expanded ingress protection and flexible mounting configurations, targeting environments where reliability and installation simplicity are paramount. Others focus on enclosures designed for harsh conditions, pairing protection with climate control and EV-related inverter solutions to address integrated deployment needs. Utility and underground-focused manufacturers are leaning into below-ground and fiber-reinforced solutions for power distribution, while large industrial suppliers are expanding standard and non-metallic enclosure ranges to serve commercial and industrial projects at scale. Modular, freestanding, and hygienic-design offerings further illustrate how product families are being shaped around maintenance, sanitation, and configuration flexibility. Universal enclosure ranges that span metal, plastic, and polyester options are also being positioned for indoor and outdoor power distribution use, reflecting a push toward cross-environment applicability.
Recent Signals from the Market
Recent product and commercial activity underscores how companies are translating these strategies into executable moves. A major die-cast enclosure supplier introduced an IP68-rated flanged variant with added surface-mount options, extending the versatility of a rugged series for applications requiring higher environmental protection and easier installation alignment. In parallel, a non-metallic conduit specialist expanded its portfolio with new conduit bodies and gang boxes, reinforcing the shift toward lightweight, corrosion-resistant protection solutions for electrical installations. On the commercial side, a diversified enclosures and electrification player reported record first-quarter sales, orders, and backlog while raising full-year guidance, reflecting sustained demand across enclosure-adjacent segments and the confidence of customers in continued infrastructure investment. These developments point to a market where capability expansion, certification readiness, and demand visibility are reinforcing each other.
Market Structure Evolution
The competitive map is evolving along three axes. Consolidation is likely to continue among mid-tier players seeking scale in certification, distribution, and material procurement, while fragmentation will persist where regional compliance nuances, specialized materials, or niche application requirements create barriers to one-size-fits-all offerings. New entrants and adjacent players are finding opportunities in modular design, integrated thermal management, and non-metallic alternatives that lower installation friction. The broader trend is toward portfolios that balance standardized, certifiable platforms with configurable options that reduce custom engineering without sacrificing performance. Companies that can navigate this balance while maintaining regulatory alignment and supply chain resilience are best positioned to capture share as procurement teams increasingly prioritize lifecycle value over upfront cost.
Future Outlook: Trends and Commercial Implications
Higher Protection Standards as a Baseline Expectation
Over the next three to five years, stronger environmental protection and safety alignment will become baseline expectations rather than premium features. This will accelerate adoption of enclosures that already meet rigorous ingress and durability criteria, especially in EV infrastructure, data center power environments, and utility deployments where downtime and exposure risks carry significant financial consequences. The commercial opportunity lies in standardizing certified, high-protection platforms that reduce project risk and accelerate approval timelines. Manufacturers and solution providers that can offer repeatable compliance across multiple environments will see stronger demand pull, while late movers may face rising rejection rates and retrofit costs.
Modular and Configurable Designs as a Growth Multiplier
Configurability is emerging as a powerful growth lever. Modular enclosure systems, interchangeable mounting options, and pre-engineered accessories allow end users to adapt solutions to changing site conditions without redesigning from scratch. This modularity also supports maintenance, expansion, and replacement cycles, aligning product economics with long-term asset management priorities. The opportunity here is not simply offering more parts, but designing families that balance standardization with flexibility, enabling faster specification, reduced inventory burden, and lower field error rates. Solutions that make specification easier and retrofit less disruptive will gain preference in recurring industrial and energy projects.
Material Diversification and Non-Metallic Expansion
Material strategy will increasingly define competitive relevance. As installation environments become more varied and corrosive-resistance requirements rise, non-metallic and hybrid material solutions will capture additional share in specific applications, while stainless steel and fiber-reinforced options continue to serve harsh or sanitary-use conditions. Manufacturers that maintain disciplined material-to-application mapping, supported by reliable sourcing and clear certification documentation, will be better equipped to manage cost swings and meet project-specific constraints. The risk lies in over-indexing on any single material category without adequate application validation, which can create exposure to substitution pressure and regional cost volatility.
Actions for Decision-Makers
For Manufacturers and Solution Providers
Invest in platform-level design that supports multiple protection ratings, mounting configurations, and material options without fragmenting the core product architecture. Prioritize certification readiness and documentation as core capabilities, since compliance now functions as a procurement prerequisite in many sectors. Expand application-specific accessory ecosystems to reduce field customization, and align supply planning with material variability so that lead times and cost structures remain stable as demand scales.
Electric Control Cabinet Market
For Investors and Strategic Buyers
Evaluate exposure to segments where protection requirements are tightening fastest and where backlog visibility suggests durable demand. Look for companies that combine modular design, material flexibility, and strong compliance footprints, since these attributes support both share gain and margin resilience. Assess supply chain and sourcing strategies as indicators of future cost control, and consider how well-positioned a company is to serve energy distribution, industrial modernization, and infrastructure build-outs rather than relying on single-sector cyclicality.
For Procurement and End-User Teams
Shift evaluation criteria toward lifecycle protection, installation efficiency, and compliance certainty rather than lowest initial unit cost. Standardize on enclosure platforms that can be specified across multiple sites and environmental conditions to reduce specification errors and replacement complexity. Where possible, prioritize solutions with clear certification alignment and modular accessory support, since these reduce project risk and improve long-term maintainability as installations evolve.
For decision-makers seeking deeper segmentation, company-level performance benchmarks, regional deployment patterns, and application-specific sizing, a comprehensive market report can provide the granularity needed to translate these trends into precise commercial plans. Detailed breakdowns of product families, end-use demand, competitive positioning, and forward demand scenarios help shorten the path from insight to execution, especially when paired with tailored assessments of where to prioritize investment, sourcing, and specification strategy.
For detailed analysis of this topic, please visit the official page: Electric Enclosure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Reinsurance Market 2026: 8.2% CAGR Trajectory and the Real Shifts Reshaping Industry Growth
By pmarketresearch, 2026-09-21
Reinsurance Market: Strategic Shifts and Commercial Opportunities in a Transforming Landscape
The global reinsurance market has entered a phase of structural expansion, driven by a combination of hardening premiums, evolving risk profiles, and accelerating digital transformation. Following a consistent upward trajectory over the past half-decade, the market surpassed the 200-billion mark in 2024 and reached 215 billion in 2025 at the base year level. Forward projections indicate sustained momentum, with the sector expected to grow at a compound annual rate of 8.2 percent through 2032, culminating in a market size approaching 345 billion. This growth is not merely a reflection of cyclical pricing but signals deeper shifts in how risk is transferred, managed, and financed across jurisdictions and asset classes. For executives and capital allocators, the numbers suggest a market that is both scaling and fragmenting in capability, creating pockets of premium returns alongside operational complexity.
Beneath the headline figures lies a market structure that remains moderately concentrated, with the top three players accounting for roughly 29 percent of total revenue and the top five holding just over 30 percent. This distribution indicates that while scale advantages persist, the market is not dominated by a handful of incumbents to the point of stifling innovation or new capacity entry. The relatively flat concentration curve between the third and fifth positions suggests competitive intensity among mid-tier and specialized carriers, particularly in non-life and life lines where pricing, underwriting discipline, and technological stack maturity diverge. The room between the leader cluster and the long tail of participants creates strategic space for platforms, service providers, and niche reinsurers that can differentiate on speed, data integration, or regulatory navigation.
Market Dynamics and Structural Challenges
Pricing Normalization Meets Risk Complexity
The post-2020 expansion reflects a market that has moved through several pricing cycles while absorbing growing exposure to climate-related losses, cyber accumulation, and demographic-driven longevity shifts. Rather than a single shock driving growth, the current phase is characterized by broad-based premium firming, improved loss recognition, and a recalibration of capital allocation toward lines with clearer risk-return profiles. This environment rewards reinsurers and brokers that can price risk with granularity and document assumptions transparently. At the same time, it raises the bar for underwriting rigor and actuarial validation, particularly where reinsured portfolios interact with complex asset structures or long-dated liabilities.
Regulatory Tightening as a Competitive Filter
A second defining challenge is the shifting regulatory architecture, which is reshaping how cedants and reinsurers prove solvency, adequacy, and collateral efficiency. In the United States, Actuarial Guideline 55, approved by the NAIC and effective from the end of 2025, requires cedants to incorporate reinsured business alongside net retained business in asset adequacy testing for statutory reserves. In Europe and comparable markets, solvency frameworks continue to mandate stringent capital equivalence, including 100 percent solvency capital requirement coverage and own-funds thresholds that support collateral-free transactions. These rules elevate the cost of compliance but also create differentiation opportunities for carriers and platforms that can operationalize asset adequacy documentation, investment accelerators, and principles-based bond definitions with minimal friction. The net effect is a market where regulatory fluency is becoming a commercial capability rather than a back-office necessity.
Talent, Automation, and the Cost of Expertise
A third pressure point is the intensifying demand for specialized actuarial and claims expertise. Updated guidelines such as AG 55, combined with tighter supervisory expectations for third-party cloud and AI deployments, increase the operational labor required to complete filings and maintain audit-ready documentation. Teams must interpret evolving asset adequacy standards, align investment matching adjustments, and demonstrate governance over automated reinsurance workflows. Where platforms and processes remain manual or fragmented, labor costs and cycle times expand, eroding margin and slowing decision velocity. Conversely, organizations that embed automation, standardized reporting, and embedded compliance into their reinsurance operations can convert this pressure into a durability advantage.
Key Growth Drivers
Digital Platforms and Automation of the Reinsurance Lifecycle
Technology is moving from experimentation to core infrastructure. Cloud-native reinsurance administration platforms are increasingly automating cessions, recoverables, commission calculations, and claims recovery across both traditional and non-proportional structures. Modular architectures allow insurers and brokers to integrate reinsurance operations with existing policy and finance systems without rip-and-replace disruptions. The emphasis is shifting from point solutions to end-to-end lifecycle coverage that spans contract initiation, ongoing administration, and retrocession management. As these platforms mature, they reduce reconciliation errors, accelerate settlements, and provide data lineage that supports regulatory exams and actuarial review. The recent wave of platform updates and launches underscores this direction, with new releases targeting automated cessions and recoverable tracking for property and casualty insurers and brokers, and sovereign-backed initiatives launching global reinsurance platforms anchored in financial free zones with institutional partners to facilitate cross-border operations.
Regulatory Modernization Enabling More Flexible Asset Deployment
Complementary regulatory changes are expanding the toolkit for matching long-tail liabilities with suitable assets. Principles-based bond definitions and investment accelerator mechanisms introduced in late 2025 are designed to facilitate more flexible asset deployment for matching adjustments within reinsurance portfolios. Alongside solvency frameworks that support collateral-free transactions when capital and own-funds thresholds are met, these developments allow market participants to optimize asset-liability alignment while preserving liquidity and governance standards. The practical implication is that reinsurers and cedants can structure transactions with greater latitude in asset selection and duration matching, provided they can evidence adequacy and maintain robust oversight. This flexibility is particularly valuable for life and annuity lines, where asset duration and crediting strategies interact directly with reinsured liabilities.
Demand-Side Shifts Toward Resilience and Capital Efficiency
On the demand side, primary insurers and corporate buyers are increasingly treating reinsurance as a strategic lever for balance-sheet resilience rather than a pure cost of risk transfer. Harder markets and elevated catastrophe volatility have reinforced the value of capacity certainty, tailored coverage, and transparent terms. At the same time, capital market participants and institutional allocators are exploring avenues to support reinsurance operations, especially in jurisdictions that offer regulatory clarity and operational efficiency. This convergence expands the ecosystem around reinsurance, creating demand for platforms and services that can coordinate ceded and assumed contracts, streamline reporting, and support multi-jurisdiction compliance. Brokers and intermediaries benefit as well, since structured automation reduces processing overhead and improves turnaround for complex placements.
Operational Cost Structures and the Value of Integrated Workflows
Cost structures are being reshaped by the interplay of technology adoption, labor scarcity, and supervisory expectations. As AI-assisted models gain traction in underwriting support, reserving, and claims triage, regulators are increasing governance, risk management, and third-party audit requirements for cloud providers and model operators. Organizations that standardize data, document model usage, and maintain audit trails can harness automation without compromising supervisory confidence. Where workflows remain siloed, the cumulative cost of manual reconciliation, rework, and compliance documentation compresses operating leverage. The emerging competitive logic is clear: integration of policy, finance, actuarial, and reinsurance administration into coherent workflows is becoming a determinant of margin and speed, especially as filing deadlines tighten and documentation expectations rise.
Competitive Landscape and Leading Strategies
The competitive field blends global reinsurers with technology and service providers, each pursuing distinct positions along the value chain. Incumbent carriers continue to anchor the market with broad risk appetite, diversified portfolios, and established distribution relationships. Their strategic emphasis typically centers on disciplined underwriting, integrated digital client tools, and robust risk-transfer and administration capabilities across life, non-life, and specialty lines. Many have built or acquired proprietary platforms and client portals to reduce friction in the placement and servicing of reinsurance contracts, reinforcing the perception of reliability and continuity that matters in long-tail and capital-intensive transactions.
Technology and software providers are carving a parallel track focused on the operational backbone of reinsurance. SaaS reinsurance administration platforms deliver modular automation for contract initiation, claims recovery, retrocession, and full lifecycle management for both traditional and non-proportional treaties. Other providers offer cloud or on-premise insurance suites that cover premiums, loss reserves, commission calculation, claims processing, and regulatory reporting for ceded and assumed contracts. These platforms increasingly target the pain points identified earlier—manual reconciliation, fragmented reporting, and audit readiness—while enabling interoperability with core policy and financial systems. The value proposition is not solely cost reduction; it is the creation of data continuity that supports solvency and asset adequacy documentation, accelerates settlements, and gives executives a clearer view of ceded exposures and recoverables.
The market is evolving through a combination of consolidation, specialization, and new entry. Scale incumbents compete on breadth and capital strength, while specialists compete on depth in particular lines or geographies. Newer entrants and platform operators compete on speed, configurability, and the ability to plug into existing ecosystems with limited disruption. Strategic differentiation is increasingly defined by three factors: the completeness of the reinsurance administration lifecycle covered, the strength of regulatory and actuarial documentation support, and the ability to operate across jurisdictions with consistent governance. As a result, partnerships between carriers, platforms, and institutional players are becoming more common, especially where an anchor in a well-regulated financial hub can streamline cross-border capacity and operations.
PW Consulting
For decision-makers evaluating partners and vendors, the practical question is not whether a provider offers a feature list, but whether its architecture reduces the cost of compliance, improves data lineage, and supports the lines and structures that matter to the organization. Providers that combine lifecycle automation with actuarial and claims support, or that can evidence alignment with asset adequacy and solvency expectations, are better positioned to capture share in a market where documentation and control are increasingly part of the commercial conversation.
Forward Outlook: Trends and Opportunities
Automation Becomes the Baseline, Not the Differentiator
Over the next three to five years, cloud-native reinsurance administration and integrated automation will move from competitive advantage to operational baseline. Organizations that standardize cessions, recoverables, commission flows, and claims recovery within connected workflows will reduce cycle times and improve the reliability of reporting used in both internal decision-making and external reviews. The commercial opportunity lies in extending these workflows to cover specialty and non-proportional structures, retrocession, and multi-currency settlements, where manual processing has historically introduced the most friction and error. Companies that achieve this baseline earlier will free managerial attention for pricing strategy, asset-liability optimization, and client service rather than administrative remediation.
Regulatory Fluency as a Commercial Capability
Regulatory and actuarial guideline evolution will continue to influence transaction structuring and platform design. Asset adequacy documentation, investment matching adjustments, and principles-based classification will require systems that can trace assumptions, evidence testing, and maintain auditability across ceded and retained portfolios. Firms that build or adopt tooling to operationalize these requirements will gain speed and credibility in filings, while those that rely on manual processes will face rising labor costs and execution risk around deadlines. The upside is not only compliance efficiency but also the ability to structure transactions with greater flexibility in asset deployment and collateral arrangements where supervisory frameworks permit, particularly in life and asset-intensive portfolios.
Market Structure Continues to Fragment in Capability, Consolidate in Ecosystems
While revenue concentration remains moderate, capability concentration will likely increase among providers that can span administration, analytics, and regulatory support within a coherent stack. Expect continued partnership activity between incumbents, platform operators, and institutional participants, especially where a regulated hub and aligned governance can reduce cross-border friction. At the same time, specialization will persist in lines with distinct underwriting, reserving, or asset dynamics, creating room for focused carriers and boutique platforms. The strategic implication is that the most resilient participants will be those that can combine clear risk appetite with interoperable technology, disciplined documentation, and the ability to scale operations without proportional increases in manual effort.
Risks and Uncertainties to Monitor
The outlook is constructive, but not without caveats. Catastrophe volatility and the accumulation of secondary perils can re-rate pricing and capacity quickly, pressuring returns and testing reserving discipline. Regulatory interpretation can shift as supervisors deepen scrutiny of AI-assisted models and third-party cloud dependencies, potentially increasing governance costs or constraining certain automation paths until standards settle. Talent constraints in actuarial and specialized claims roles may continue to elevate operational expenses where workflows are not sufficiently automated or standardized. Finally, macro and capital market dynamics can affect asset deployment strategies and the attractiveness of collateral-free structures, influencing transaction economics in life and non-life lines alike. Participants should therefore pair growth ambitions with scenario planning, data quality, and flexible operating models.
Strategic Implications for Decision-Makers
For Executives and Strategy Teams
Prioritize integration over point fixes. Decision velocity and margin protection increasingly depend on connected workflows that span policy, finance, actuarial, and reinsurance administration. Establish clear ownership of data lineage and documentation so that asset adequacy testing, solvency reporting, and recoverable tracking can be produced consistently and on time. Evaluate partners and platforms against their ability to cover the full lifecycle, support the lines and structures most relevant to the portfolio, and demonstrate governance aligned with supervisory expectations. Where feasible, sequence adoption to first reduce the highest-friction manual processes, then extend automation to specialty and non-proportional structures and multi-currency operations.
Worldwide Real Estate Insurance Market
For Investors and Capital Allocators
Assess exposure and resilience across the value chain rather than relying on headline market size alone. Differentiate between carriers with diversified, disciplined underwriting and those more exposed to concentrated catastrophe or cyber accumulation. In technology and service providers, focus on evidence of workflow completeness, customer retention, and the ability to reduce compliance and reconciliation costs, since these qualities translate into durable operating leverage as regulatory and documentation demands rise. Consider jurisdictional and partnership dynamics that can lower cross-border friction, while monitoring the regulatory trajectory for AI and cloud governance, which may affect cost structures and deployment options in the medium term.
For Procurement and Vendor Selection Teams
FrameRFP criteria around outcomes rather than feature counts. Define requirements for automated cessions, recoverable tracking, commission handling, claims support, and audit-ready reporting, and verify how each candidate maps to existing policy and financial systems. Require demonstrations of data lineage, documentation support for asset adequacy and solvency contexts, and clear migration or interoperability plans to avoid rip-and-replace risk. Weight vendor stability, roadmap coherence, and support for multi-jurisdiction operations where relevant, and build pilot metrics around cycle-time reduction, error reduction, and documentation completeness so that adoption decisions are anchored in measurable operational improvement.
The reinsurance market is scaling within a framework of rising expectations for speed, transparency, and regulatory discipline. Those that treat technology, data, and compliance fluency as core commercial capabilities will be better positioned to absorb complexity, protect margin, and access capacity where it is most valuable. For readers seeking a deeper segmentation of regional and line-level dynamics, detailed revenue paths across the forecast horizon, and tailored recommendations calibrated to specific portfolio structures, the full research report provides the granular data and scenario analysis needed to convert these strategic signals into concrete plans.
Insurance Market
For detailed analysis of this topic, please visit the official page: Reinsurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com